The sample copy of this report is available for access.
The North America GPU Liquid Cooling Market is expected to reach USD 9.0 billion by 2032, growing at a CAGR of 23.8% during (2026 – 2033).
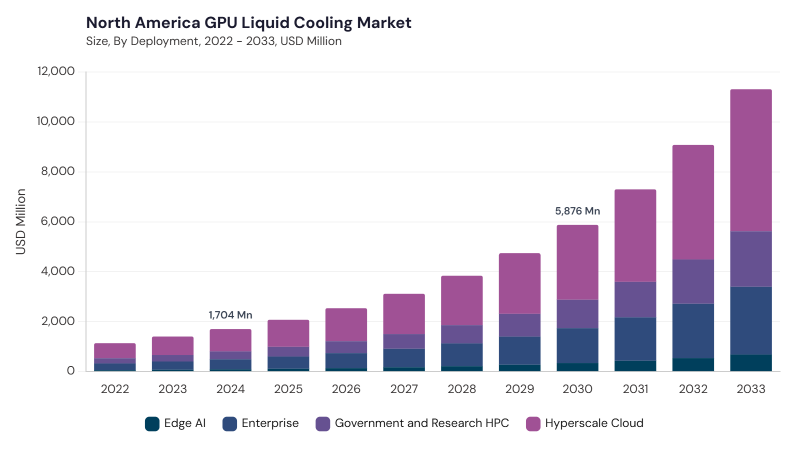
GPU liquid cooling across North America evolved from niche deployments in supercomputing and specialized HPC environments into an essential thermal-management technology for AI-intensive infrastructure. Rising GPU power density gradually exposed the limitations of conventional air cooling, accelerating adoption of direct-to-chip and immersion approaches. Hyperscale cloud providers and AI data centers played a major role in validating large-scale liquid cooling deployments. Continued advances in coolant distribution, thermal monitoring, modular system design, and integration have supported broader adoption across high-density computing environments.
Rapid expansion of AI and machine learning workloads, increasing GPU thermal output, sustainability requirements, and hyperscale infrastructure development are reshaping market demand. Direct-to-chip and immersion cooling are gaining importance because they improve heat removal, enable denser GPU configurations, and reduce cooling-related energy consumption. Modular and scalable architectures are also helping operators accommodate evolving GPU generations without complete infrastructure redesigns. At the same time, regulatory focus on energy efficiency and environmental performance is strengthening demand for advanced, reliable, and resource-efficient cooling systems.
Based on Cooling Type, the market is segmented into Single-Phase and Two-Phase. The Single-Phase market dominated the North America GPU Liquid Cooling Market by Cooling Type in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 6.6 billion by 2032, growing at a CAGR of 23.4 % during the forecast period. The Two-Phase market is expected to witness a CAGR of 24.9% during (2026 - 2033).
Single-Phase cooling uses liquid coolant to absorb GPU heat without changing phase, offering stable thermal performance, simpler maintenance, and easier integration across enterprise, cloud, and AI environments. Improvements in pumps, heat exchangers, cold plates, and hybrid architectures continue to strengthen its scalability. Two-Phase cooling uses coolant phase change to achieve greater heat-transfer efficiency and is increasingly relevant for extreme GPU thermal densities. Its higher complexity is balanced by strong potential across AI supercomputing, hyperscale facilities, and next-generation GPU systems requiring compact, high-capacity thermal management.
Based on Cooling Level, the market is segmented into Component-Level Cooling and Server Rack-Level Cooling. The Component-Level Cooling market dominated the North America GPU Liquid Cooling Market by Cooling Level in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 5.5 billion by 2032, growing at a CAGR of 23.4 % during the forecast period. The Server Rack-Level Cooling market is expected to witness a CAGR of 24.4% during (2026 - 2033).
Component-Level Cooling removes heat directly from individual chips or modules through technologies such as cold plates and precision liquid channels, reducing hotspots and supporting consistent GPU performance in AI and HPC systems. Advances in microchannel designs and thermal materials are improving localized heat transfer as component power densities increase. Server Rack-Level Cooling provides centralized thermal management across multiple GPU servers using coolant distribution units, piping, and integrated rack architectures. It is becoming increasingly relevant for hyperscale and enterprise facilities deploying dense GPU clusters that require scalable, system-level cooling and improved energy efficiency.
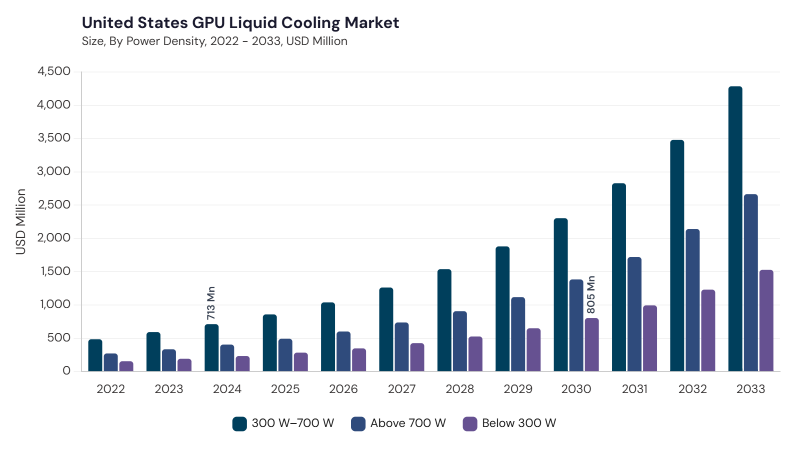
Based on Power Density, the market is segmented into 300 W–700 W, Above 700 W, and Below 300 W. The 300 W–700 W category represents a major transition zone where conventional air cooling becomes increasingly constrained and direct-to-chip or hybrid liquid cooling provides stronger thermal efficiency.
Above 700 W addresses extreme GPU power densities associated with advanced AI accelerators, hyperscale clusters, and intensive HPC workloads, driving demand for high-capacity direct liquid and immersion cooling. Below 300 W serves lower-power accelerators, edge computing, moderate AI inference, and specialized applications where targeted liquid cooling can improve reliability, noise control, space utilization, and thermal stability.
Based on Deployment, the market is segmented into Hyperscale Cloud, Enterprise, Government and Research HPC, and Edge AI. Hyperscale Cloud environments require scalable liquid cooling to support dense AI and machine learning infrastructure while reducing thermal constraints and cooling energy requirements. Enterprise deployments increasingly use flexible and retrofit-friendly systems for private AI, analytics, rendering, and business-critical GPU workloads.
Government and Research HPC facilities rely on specialized liquid cooling for scientific simulations, supercomputing, defense research, and prolonged high-intensity computation. Edge AI remains an emerging application requiring compact, modular, low-maintenance cooling for distributed GPU systems operating near data sources under space and infrastructure limitations.
Free Valuable Insights: The Global GPU Liquid Cooling Market will hit USD 37.2 Billion billion by 2033, at a CAGR of 24.5%
Based on Country, the market is segmented into US, Canada, Mexico, and Rest of North America. The US market dominated the North America GPU Liquid Cooling Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 6.8 billion by 2032, growing at a CAGR of 23 % during the forecast period. The Canada market is expected to witness a CAGR of 26.5% during (2026 - 2033). Additionally, The Mexico market is expected to witness a CAGR of 25.7% during (2026 - 2033).
Across North America, GPU liquid cooling adoption is increasingly influenced by AI infrastructure, higher rack densities, sustainability targets, and advanced data center development. The US is advancing direct-to-chip, hybrid, closed-loop, and modular cooling architectures for AI-intensive facilities, while Canada emphasizes energy efficiency, environmental performance, two-phase technologies, and customized solutions for HPC and AI workloads. Mexico is progressing through direct-to-chip and immersion cooling, localized service capabilities, high-density GPU deployments, and collaboration between cooling providers and hardware manufacturers. Rest of North America continues to develop sustainable cooling, AI-driven thermal management, edge-oriented modular systems, localized infrastructure, and scalable solutions for evolving GPU environments.
By Cooling Type
By Cooling Level
By Power Density
By Deployment
By Country
Set to reach $9.0 Billion by 2032, growing at 23.8% CAGR during 2026-2033.
The US leads with $6.8 billion by 2032, growing at 23% CAGR during the forecast period.
Rising enterprise cloud adoption and AI-driven workloads are the main catalysts.
Single-Phase segment will reach $6.6 billion by 2032, growing at 23.4% CAGR during the forecast period.
Canada market is expected to witness a CAGR of 26.5% during 2026-2033.
Component-Level Cooling will reach $5.5 billion by 2032, growing at 23.4% CAGR during the forecast period.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.

 Unique Offerings