The sample copy of this report is available for access.
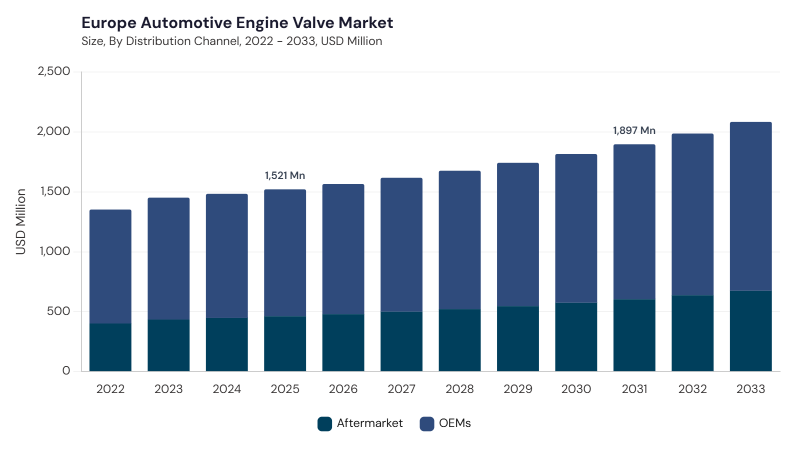
The Europe Automotive Engine Valve Market is expected to reach USD 1896.9 million by 2031, growing at a CAGR of 4.2% during (2026 - 2033).
The Europe Automotive Engine Valve Market originated with early internal combustion engines, where engine valves regulated airflow, fuel-mixture intake, and exhaust gas expulsion. Initially, valves were simple steel-alloy components with limited lifespan and performance efficiency, but advances in metallurgy, coatings, precision manufacturing, and complex valve geometries gradually transformed them into highly engineered engine components. Over time, the shift from carbureted to fuel-injected engines, variable valve timing, lightweight materials such as titanium and advanced ceramics, hybrid powertrain requirements, and stringent European regulatory frameworks moved the market toward durable, efficient, and emission-compliant valve systems.
Current market growth is shaped by emission compliance, lightweight material integration, hybrid powertrain adoption, advanced coatings, and smart manufacturing. Manufacturers are increasingly developing valves with heat-resistant alloys, advanced surface treatments, titanium materials, composite technologies, variable valve timing, solenoid-actuated valve mechanisms, precision machining, and additive manufacturing support. Demand is also rising for valves that withstand higher combustion temperatures, reduce reciprocating mass, improve fuel economy, support hybrid engine start-stop cycles, and align with Europe’s environmental regulations, OEM requirements, and evolving propulsion systems.
Based on Distribution Channel, the market is segmented into OEMs and Aftermarket. The OEMs market dominated the Europe Automotive Engine Valve Market by Distribution Channel in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 1292.7 million by 2031, growing at a CAGR of 3.8 % during the forecast period. The Aftermarket market is expected to witness a CAGR of 5% during (2026 - 2033).
OEMs remain the leading distribution channel as they support new vehicle production, Euro emission compliance, high-grade materials, advanced coatings, hybrid powertrain integration, turbocharged engines, factory-level quality requirements, and long-term automaker partnerships. Aftermarket represents an emerging presence through Europe’s sizeable vehicle parc, routine engine servicing, remanufacturing activities, replacement demand for high-mileage vehicles, independent garages, authorized service centers, online distributors, and steady demand for durable and compatible engine valve replacements.
Based on Type, the market is segmented into Mono Metallic, Bimetallic, and Hollow. The Mono Metallic market dominated the Europe Automotive Engine Valve Market by Type in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 702.2 million by 2031, growing at a CAGR of 3.5 % during the forecast period. The Bimetallic market is expected to witness a CAGR of 4.5% during (2026 - 2033). Additionally, The Hollow market is expected to witness highest CAGR of 4.6% during (2026 - 2033).
Mono Metallic valves remain the leading type as they offer single-metal construction, cost efficiency, consistent thermal conductivity, mechanical strength, reliable performance, and suitability for conventional gasoline and diesel engines, mass-market vehicles, and replacement parts. Bimetallic valves maintain a significant standing through improved thermal resilience, mechanical durability, valve seat recession resistance, longer service life, turbocharged engine suitability, and relevance in mid-to-high-performance gasoline, diesel, and hybrid powertrains. Hollow valves represent a promising outlook through internal cavity design, sodium or alternative cooling agents, reduced valve weight, improved heat dissipation, higher engine-speed support, turbocharged engine compatibility, and use in sports cars, luxury vehicles, and commercial transportation.
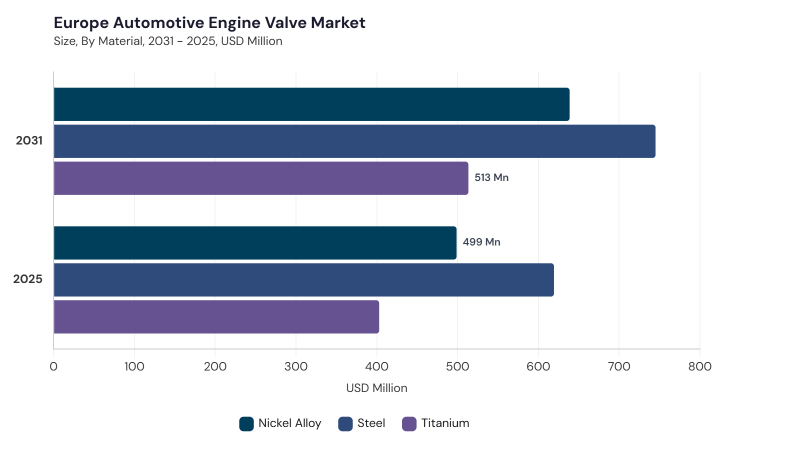
Based on Material, the market is segmented into Steel, Nickel Alloy, and Titanium. Steel remains the leading material as it provides mechanical strength, cost efficiency, thermal conductivity, corrosion resistance, heat-treatment compatibility, coating adaptability, and broad use across intake and exhaust valves in gasoline and diesel engines.
Nickel Alloy holds a substantial presence through high-temperature strength, oxidation stability, corrosion resistance, exhaust-valve suitability, severe thermal cycling tolerance, turbocharged engine use, and demand from premium, heavy-duty, luxury, and high-performance engines. Titanium maintains an advancing presence through high strength-to-weight ratio, corrosion resistance, reduced valve train inertia, improved engine responsiveness, high-temperature tolerance, and application in sports, racing, and performance-oriented vehicles.
Based on Vehicle Type, the market is segmented into Passenger Vehicles, Light Commercial Vehicles, and Heavy Commercial Vehicles. Passenger Vehicles remain the leading vehicle type as they include compact cars, sedans, SUVs, and electric hybrids requiring valves for combustion efficiency, emission compliance, turbocharging, direct fuel injection, variable valve timing, lightweight materials, and lower friction.
Light Commercial Vehicles hold a substantial foothold through vans, small trucks, urban delivery operations, tradespeople, service fleets, frequent stop-start cycles, diesel engine use, durable valve materials, and cost-efficient operation. Heavy Commercial Vehicles represent a promising presence through trucks, buses, freight carriers, long-haul transport, construction, distribution, diesel engines, high-load operating cycles, thermal stability, wear resistance, advanced coatings, and compatibility with renewable diesel or biomethane engines.
Free Valuable Insights: The Worldwide Automotive Engine Valve Market is projected to reach USD 8148.5 Million billion by 2033, at a CAGR of 4.9%
Based on Country, the market is segmented into Germany, UK, France, Russia, Spain, Italy, and Rest of Europe. The Germany market dominated the Europe Automotive Engine Valve Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 447.1 million by 2031, growing at a CAGR of 3 % during the forecast period. The UK market is expected to witness a CAGR of 2.6% during (2026 - 2033). Additionally, The France market is expected to witness a CAGR of 4.9% during (2026 - 2033).
Germany is shaped by lightweight durable materials, variable valve timing, camless valve systems, hybrid compatibility, advanced coatings, automation, and precision machining, while the UK reflects CO2 emission pressure, fuel efficiency mandates, hybrid powertrains, advanced surface treatments, titanium alloys, and digital manufacturing. France is supported by lightweight titanium and stainless-steel valves, hybrid and alternative fuel compatibility, Industry 4.0 production, automation, real-time quality monitoring, and additive manufacturing. Russia is influenced by emissions and fuel-efficiency pressure, turbocharged and downsized engines, localization, import substitution, advanced alloys, and automated quality inspection, whereas Spain is advancing through hydrogen and alternative fuel compatibility, variable valve actuation, AI-enabled inspection, localized production, and smart manufacturing. Italy is driven by lightweight alloys, CAD and FEA-supported valve design, hybrid powertrain requirements, fatigue resistance, corrosion protection, and Industry 4.0 practices, while Rest of Europe is shaped by fuel economy regulation, turbocharged downsized engines, mild hybrid and alternative fuel integration, high-temperature alloys, electronic valve actuation, and regional manufacturing or R&D localization.
By Distribution Channel
By Type
By Material
By Vehicle Type
By Country
Set to reach $1896.9 Million by 2031, growing at 4.2% CAGR during 2026-2033.
Germany leads with a market value of $447.1 million by 2031, growing at a 3% CAGR during 2026-2033.
Rising demand from OEMs, projected to reach $1292.7 million by 2031 at a 3.8% CAGR during 2026-2033.
Mono Metallic segment to reach $702.2 million by 2031, growing at a 3.5% CAGR during 2026-2033.
Aftermarket segment is expected to witness a 5% CAGR during 2026-2033.
France market is expected to witness a 4.9% CAGR during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.
 Unique Offerings