The sample copy of this report is available for access.
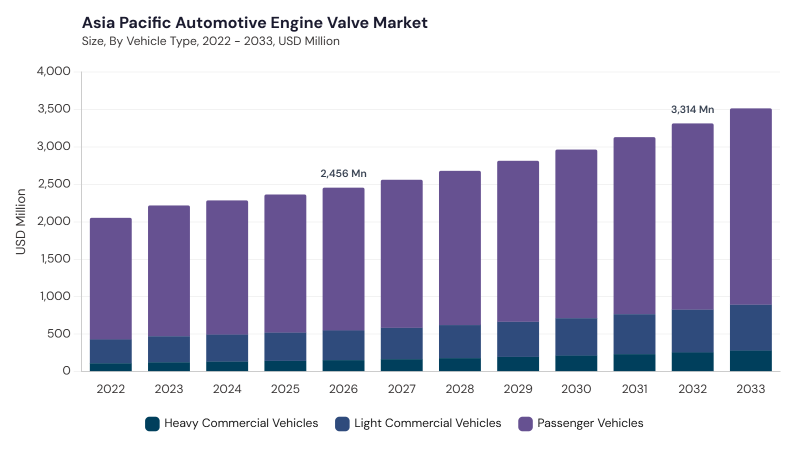
The Asia Pacific Automotive Engine Valve Market is expected to reach USD 2.9 billion by 2030, growing at a CAGR of 5.3% during (2026 - 2033).
The Asia Pacific Automotive Engine Valve Market evolved from the region’s early automobile manufacturing and component supply base, where basic metallurgical techniques primarily served emerging local assembly plants. As China, Japan, South Korea, India, and other regional markets became major vehicle producers, engine valve manufacturing advanced from traditional forging and machining toward precision casting, high-performance alloys, and more durable valve designs. Over time, emission-compliant engine technologies, lightweight heat-resistant materials, higher combustion pressure requirements, manufacturing precision, and integration with engine control technologies transformed the market from standard valve supply toward advanced, durable, and environmentally aligned engine valve solutions.
Current market growth is shaped by emission norm compliance, lightweight engine development, hybrid powertrain optimization, advanced coatings, and localized manufacturing. Manufacturers are increasingly using advanced alloy compositions, titanium materials, composite-based valves, surface treatments, precision casting, additive manufacturing, automation, and digitalized production systems to improve durability, thermal efficiency, sealing performance, and product scalability. Demand is also rising for engine valves that support stop-start technologies, variable valve timing systems, downsized engines, turbocharging, fuel economy improvement, and cost-effective supply near major Asia Pacific automotive hubs.
Based on Distribution Channel, the market is segmented into OEMs and Aftermarket. The OEMs market dominated the Asia Pacific Automotive Engine Valve Market by Distribution Channel in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 2.0 billion by 2030, growing at a CAGR of 4.9 % during the forecast period. The Aftermarket market is expected to witness a CAGR of 6.1% during (2026 - 2033).
OEMs remain the leading distribution channel as they support new vehicle assembly, strict automaker specifications, emission compliance, turbocharging, variable valve timing, lightweight materials, hybrid powertrain optimization, and long-term supplier partnerships. Aftermarket represents a promising foothold through a large vehicle population in operation, longer ownership cycles, developing-economy repair demand, independent garages, authorized service centers, e-commerce channels, replacement requirements, and cost-efficient valves compatible with diverse vehicle models and engine types.
Based on Type, the market is segmented into Mono Metallic, Bimetallic, and Hollow. The Mono Metallic market dominated the Asia Pacific Automotive Engine Valve Market by Type in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 1.1 billion by 2030, growing at a CAGR of 4.6 % during the forecast period. The Bimetallic market is expected to witness a CAGR of 5.6% during (2026 - 2033). Additionally, The Hollow market is expected to witness highest CAGR of 5.7% during (2026 - 2033).
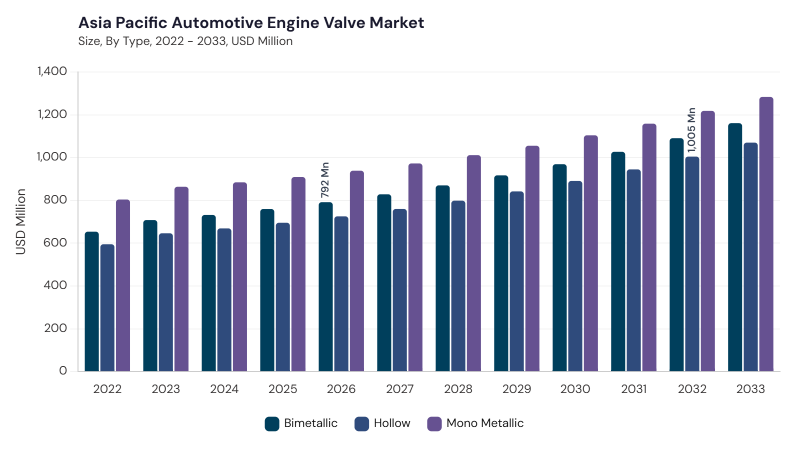
Mono Metallic valves remain the leading type as they provide single-alloy construction, mechanical strength, thermal endurance, cost efficiency, simple manufacturing, high-volume production support, and suitability for standard gasoline and diesel engines in mass-market vehicles. Bimetallic valves hold a significant presence through differentiated stem and head properties, improved heat dissipation, corrosion resistance, wear resistance, strength-to-weight benefits, and relevance in mid-to-high-range vehicles, turbocharged engines, and hybrid platforms. Hollow valves represent an emerging presence through internal cavity design, sodium or proprietary cooling fluids, reduced valve temperature, improved heat transfer, lower valve weight, higher compression-ratio support, and suitability for high-performance, heavy-duty, commercial, and alternative fuel engines.
Based on Material, the market is segmented into Steel, Nickel Alloy, and Titanium. Steel remains the leading material as it offers mechanical strength, cost-effectiveness, manufacturability, wear resistance, fatigue life, heat-treatment compatibility, coating support, and broad use across standard gasoline and diesel engines in passenger and commercial vehicles.
Nickel Alloy maintains a substantial standing through high-temperature strength, corrosion resistance, oxidation resistance, creep resistance, exhaust-valve suitability, turbocharged powertrain use, diesel engine relevance, and heavy-duty commercial applications. Titanium holds a promising outlook through low density, high tensile strength, corrosion resistance, reduced reciprocating mass, rapid actuation, improved throttle response, high-performance applications, premium vehicles, sports models, and advanced two-wheeler use.
Based on Vehicle Type, the market is segmented into Passenger Vehicles, Light Commercial Vehicles, and Heavy Commercial Vehicles. Passenger Vehicles remain the leading vehicle type as they include sedans, hatchbacks, SUVs, compact cars, gasoline models, hybrid platforms, variable valve timing, low-friction coatings, lightweight materials, fuel economy improvement, emission compliance, and high-volume regional production.
Light Commercial Vehicles hold a significant foothold through vans, pickups, mini trucks, intra-city goods movement, last-mile delivery, frequent stop-and-go cycles, variable load conditions, hardened valve seats, erosion-resistant coatings, and natural gas or hybrid LCV requirements. Heavy Commercial Vehicles maintain an advancing presence through buses, large trucks, construction machinery, mining, long-distance freight, high-load engines, extended duty cycles, advanced alloys, EGR-compatible valves, electronically controlled valve timing, and precision manufacturing for longer overhaul intervals.
Free Valuable Insights: Automotive Engine Valve Market is Predicted to reach USD 8148.5 Million billion by 2033, at a CAGR of 4.9%
Based on Country, the market is segmented into China, Japan, India, South Korea, Australia, Malaysia, and Rest of Asia Pacific. The China market dominated the Asia Pacific Automotive Engine Valve Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 1.3 billion by 2030, growing at a CAGR of 4.2 % during the forecast period. The Japan market is expected to witness a CAGR of 4.4% during (2026 - 2033). Additionally, The India market is expected to witness a CAGR of 6.3% during (2026 - 2033).
China is shaped by localization, advanced materials, digital simulation, robotic machining, smart manufacturing, and engine management software development, while Japan reflects lightweight alloys, composite materials, powder metallurgy, additive manufacturing, variable valve timing compatibility, hybrid powertrain requirements, and precision manufacturing. India is supported by emission compliance, advanced heat-resistant alloys, coatings, electric and hybrid vehicle influence, CNC machining, Industry 4.0 production, and domestic supply-chain expansion. South Korea is advancing through emission reduction, hard chrome plating, precision engineering, smart manufacturing, OEM collaboration, proprietary coatings, and just-in-time supply models, whereas Australia is influenced by lightweight valve materials, variable valve timing, electronic actuation, mild hybrid and ICE variants, precision engineering, and digital manufacturing. Malaysia is driven by cleaner engine compatibility, variable valve timing-compatible valves, localized component production, Industry 4.0 technologies, IoT-enabled machinery, and process automation, while Rest of Asia Pacific is shaped by variable valve timing adoption, advanced alloys, surface treatments, localization, supply-chain resilience, electronic actuation, and regional OEM partnerships.
By Distribution Channel
By Type
By Material
By Vehicle Type
By Country
Set to reach $2.9 Billion by 2030, growing at 5.3% CAGR during 2026-2033.
China leads with a market value of USD 1.3 billion by 2030, growing at a CAGR of 4.2% during 2026-2033.
OEMs dominate with a market value of USD 2.0 billion by 2030, growing at a CAGR of 4.9% during 2026-2033.
The Mono Metallic segment hits USD 1.1 billion by 2030, growing at a CAGR of 4.6% during 2026-2033.
India is expected to witness a CAGR of 6.3% during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.
 Unique Offerings