The sample copy of this report is available for access.
The North America Real Estate Software Market is expected to reach USD 7.7 billion by 2032, growing at a CAGR of 11.3% during (2026 – 2033).
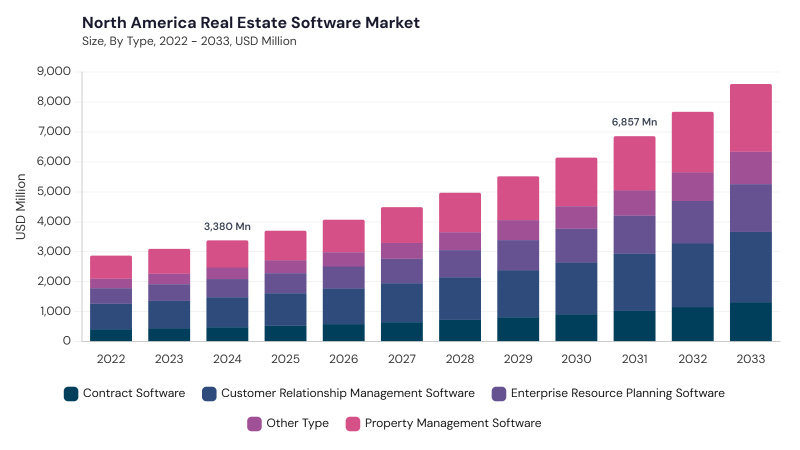
The North America Real Estate Software Market originated from the digitization of property listings, lease records, client databases, and transaction documentation. Earlier platforms mainly helped brokers, agents, landlords, and property managers replace paper-based workflows with basic CRM, accounting, and leasing tools. As internet connectivity, mobile access, cloud computing, and SaaS delivery improved, software adoption moved beyond record-keeping into centralized property operations and portfolio visibility. The rise of AI, big data analytics, virtual tours, digital contracts, and mobile-first workflows further changed how real estate firms manage assets, tenants, leads, and investment decisions.
The North America Real Estate Software Market is progressing through AI automation, cloud-based deployment, cybersecurity upgrades, compliance-focused workflows, and integrated PropTech ecosystems. Vendors are embedding predictive analytics, automated lease abstraction, tenant behavior analysis, property valuation models, smart maintenance tools, and portfolio dashboards to improve decision-making. Cloud and SaaS models are helping firms reduce IT burden, support remote teams, enable real-time reporting, and scale across multiple property types. At the same time, privacy laws, cyber risks, fair housing rules, investor transparency requirements, and data security expectations are increasing demand for secure and compliance-ready platforms.
Based on Deployment, the market is segmented into Cloud and On-Premise. The Cloud market dominated the North America Real Estate Software Market by Deployment in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 5.3 billion by 2032, growing at a CAGR of 10.9 % during the forecast period. The On-premise market is expected to witness a CAGR of 12.2% during (2026 - 2033).
Cloud deployment leads due to growing demand for remote accessibility, real-time data synchronization, subscription-based pricing, mobile workflows, and lower infrastructure requirements. It supports MLS integration, CRM functions, lease administration, analytics dashboards, tenant portals, and property management tools across distributed teams. Cloud platforms also allow faster upgrades, stronger interoperability, easier AI integration, and flexible scaling for firms managing residential, commercial, and mixed-use assets. On-Premise remains relevant among large enterprises, REITs, and firms handling sensitive investor, tenant, and financial data where internal control, customization, legacy integration, and strict security governance remain important.
Based on Type, the market is segmented into Customer Relationship Management Software, Property Management Software, Enterprise Resource Planning Software, Contract Software, and Other Type. The Customer Relationship Management Software market dominated the North America Real Estate Software Market by Type in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 2.1 billion by 2032, growing at a CAGR of 10.3 % during the forecast period. The Property Management Software market is expected to witness a CAGR of 11% during (2026 - 2033). Additionally, The Enterprise Resource Planning Software market is expected to witness highest CAGR of 11.6% during (2026 - 2033).
Customer Relationship Management Software leads because agents, brokers, developers, and real estate firms depend on lead tracking, client communication, sales pipeline management, marketing automation, and personalized engagement. AI-based CRM tools are improving lead scoring, client behavior prediction, follow-up timing, and transaction conversion across competitive real estate markets. Property Management Software holds strong demand through rent collection, tenant screening, lease administration, maintenance scheduling, resident portals, and compliance workflows. Enterprise Resource Planning Software, Contract Software, and Other Type gain adoption through financial control, project coordination, e-signatures, document automation, analytics, virtual tours, and specialized real estate intelligence tools.
Based on Application, the market is segmented into Residential and Commercial. Residential leads due to the large base of homes, apartments, multi-family units, rental portfolios, and tenant-facing operations requiring digital management. Software supports rent automation, tenant screening, maintenance tracking, lease renewals, communication portals, payment processing, and compliance with tenant-related regulations.
AI-enabled screening, predictive maintenance, mobile tenant services, and cloud-based property management are strengthening residential adoption. Commercial applications remain important for office, retail, industrial, hospitality, and mixed-use properties where lease administration, portfolio analytics, occupancy tracking, space utilization, asset valuation, tenant experience, and financial performance reporting are central requirements.
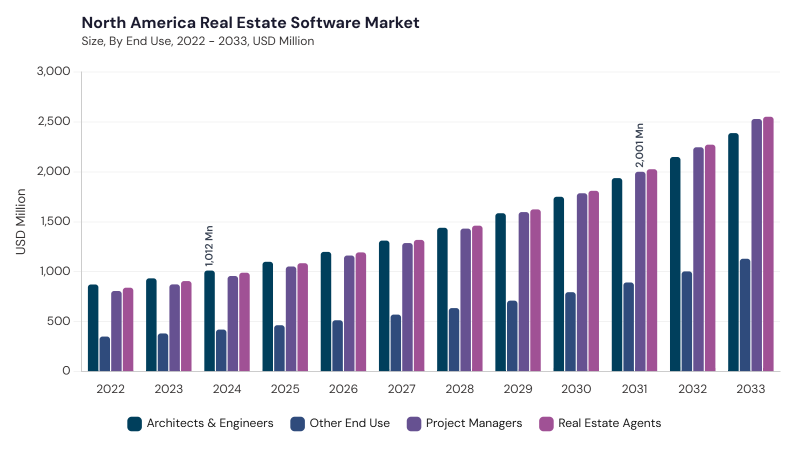
Based on End Use, the market is segmented into Architects & Engineers, Real Estate Agents, Project Managers, and Other End Use. Architects & Engineers lead due to rising use of CAD, BIM, design collaboration tools, structural modeling, zoning review, feasibility analysis, energy simulation, and documentation platforms in real estate development. These users rely on digital tools to improve design accuracy, regulatory submission, sustainability planning, and project coordination.
Real Estate Agents use CRM, listing management, MLS integration, virtual tours, pricing analytics, digital contracts, and mobile communication tools to manage clients and transactions. Project Managers adopt scheduling, budgeting, document control, resource planning, and BIM-linked coordination tools, while Other End Use includes facility managers, investors, landlords, asset managers, legal teams, and corporate real estate users.
Free Valuable Insights: The Global Real Estate Software Market will hit USD 25.3 Billion billion by 2033, at a CAGR of 11.9%
Based on Country, the market is segmented into US, Canada, Mexico, and Rest of North America. The US market dominated the North America Real Estate Software Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 5.2 billion by 2032, growing at a CAGR of 10.5 % during the forecast period. The Canada market is expected to witness a CAGR of 13% during (2026 - 2033). Additionally, The Mexico market is expected to witness a CAGR of 12.6% during (2026 - 2033).
The US leads due to its large real estate transaction base, strong PropTech ecosystem, institutional property ownership, REIT activity, cloud adoption, AI-enabled analytics, and mature software vendor presence. Canada supports demand through digital property management, provincial compliance needs, smart building tools, PropTech startups, and AI-based investment analytics. Mexico is advancing through growing urban real estate activity, cloud-hosted platforms, compliance-focused contract tools, mobile adoption, and demand for localized real estate workflows. Rest of North America benefits from SaaS adoption, property management digitization, AI-based portfolio tools, and regional demand for affordable, scalable, and compliance-ready real estate software.
By Deployment
By Type
By Application
By End Use
By Country
Set to reach $7.7 Billion by 2032, growing at 11.3% CAGR during 2026-2033.
The US leads with $5.2 billion by 2032, growing at a 10.5% CAGR during the forecast period.
Cloud deployment segment dominates, reaching $5.3 billion by 2032 at a 10.9% CAGR during the forecast period.
Canada's market is expected to grow at a 13% CAGR during 2026-2033.
The on-premise market is expected to witness a 12.2% CAGR during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.

 Unique Offerings