The sample copy of this report is available for access.
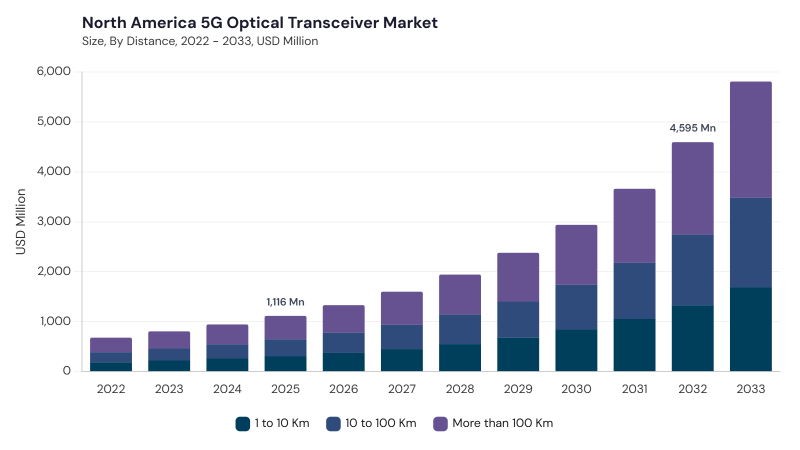
The North America 5G Optical Transceiver Market is expected to reach USD 4.5 billion by 2032, growing at a CAGR of 23.4% during (2026 - 2033).
Across North America, the 5G Optical Transceiver Market evolved alongside fiber-optic network modernization and the transition from conventional mobile infrastructure toward distributed 5G architectures. Optical transceivers initially supported telecom backbone, metro, broadband, and LTE networks before expanding into 5G fronthaul, midhaul, and backhaul applications. Network densification, small-cell deployment, centralized and cloud-based radio access networks, and greater fiber connectivity increased demand for high-speed, low-latency optical links. The technology landscape has consequently progressed from lower-speed modules toward 25G, 100G, 400G, and emerging 800G connectivity supporting both telecom transport and data-center infrastructure.
Higher transmission speeds, network densification, AI-oriented data centers, energy efficiency, and supply-chain resilience are shaping current market development. Telecom operators increasingly require compact, high-bandwidth optical transceivers capable of supporting dense 5G radio environments while reducing power consumption and deployment complexity. Expansion of hyperscale and edge data centers is accelerating development of 400G and 800G technologies, silicon photonics, coherent optics, digital signal processing, and integrated photonic architectures. Greater attention to interoperability, product qualification, network resilience, cybersecurity, and localized supply chains is also influencing procurement and technology strategies across North America.
Based on Infrastructure, the market is segmented into 5G Fronthaul and 5G Midhaul/Backhaul. The 5G Fronthaul market dominated the North America 5G Optical Transceiver Market by Infrastructure in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 3.3 billion by 2032, growing at a CAGR of 23.2 % during the forecast period. The 5G Midhaul/Backhaul market is expected to witness a CAGR of 24.1% during (2026 - 2033).
5G Fronthaul provides low-latency, high-bandwidth optical connectivity between radio units and processing infrastructure, making compact and energy-efficient transceivers important for dense mobile deployments. Increasing 25G and 50G connectivity requirements, massive MIMO, and distributed antenna systems continue to influence fronthaul architectures. 5G Midhaul/Backhaul aggregates traffic from radio and distributed network elements toward centralized units, metro facilities, and core networks, requiring greater reach, scalability, spectral efficiency, and higher transmission rates. Expansion of 100G and 400G connectivity, coherent optics, digital signal processing, and network virtualization is strengthening this segment.
Based on Distance, the market is segmented into More than 100 Km, 10 to 100 Km, and 1 to 10 Km. The More than 100 Km market dominated the North America 5G Optical Transceiver Market by Distance in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 1.8 billion by 2032, growing at a CAGR of 22.7 % during the forecast period. The 10 to 100 Km market is expected to witness a CAGR of 23.9% during (2026 - 2033). Additionally, The 1 to 10 Km market is expected to witness highest CAGR of 24% during (2026 - 2033).
More than 100 Km solutions support long-haul transport requiring high-capacity transmission, advanced modulation, coherent detection, wavelength flexibility, and strong signal integrity. The 10 to 100 Km category serves metropolitan and regional links connecting aggregation nodes, distributed units, centralized units, edge facilities, and data centers while balancing reach, bandwidth, latency, and cost. The 1 to 10 Km segment addresses localized optical connectivity across small cells, indoor networks, edge sites, and dense data-center environments where compact modules, low latency, power efficiency, and deployment density are important.
Based on Wavelength, the market is segmented into 1310 nm Band, 850 nm Band, and Other Wavelength. The 1310 nm Band market dominated the North America 5G Optical Transceiver Market by Wavelength in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 1.9 billion by 2032, growing at a CAGR of 22.7 % during the forecast period. The 850 nm Band market is expected to witness a CAGR of 24% during (2026 - 2033). Additionally, The Other Wavelength market is expected to witness highest CAGR of 23.9% during (2026 - 2033).
The 1310 nm Band supports medium-distance single-mode fiber connectivity and offers a balance of reach, signal integrity, compatibility, and cost across metropolitan 5G networks. The 850 nm Band primarily serves shorter-reach, high-bandwidth links using multimode fiber within base-station facilities, edge locations, and data-center environments, supported by mature VCSEL technology. Other Wavelength includes bands such as 1490 nm and 1550 nm used for specialized metro, long-haul, WDM, and high-capacity transport applications. Coherent optics, programmable wavelength assignment, and wavelength-division multiplexing are expanding flexibility across these configurations.
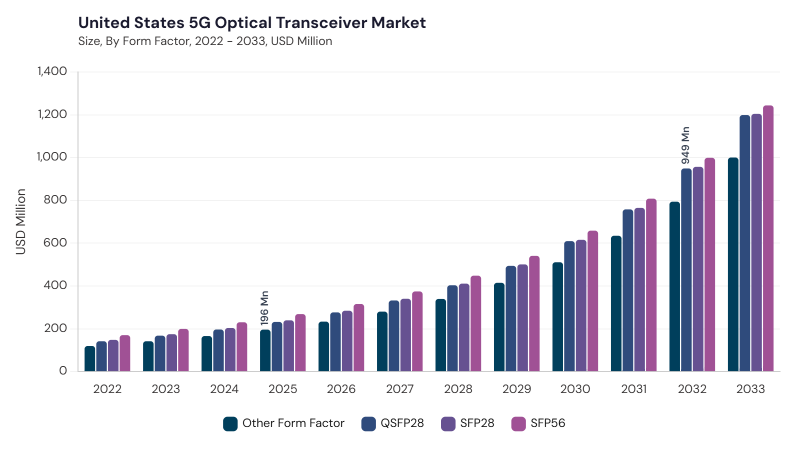
Based on Form Factor, the market is segmented into SFP56, SFP28, QSFP28, and Other Form Factor. SFP56 supports compact fronthaul and midhaul deployments requiring balanced bandwidth, footprint, and energy consumption. SFP28 remains widely used across 25G access, edge, small-cell, and transport networks because of its established ecosystem and compatibility with existing equipment.
QSFP28 supports higher-throughput applications by combining multiple lanes for aggregation, backhaul, core, and data-intensive environments. Other Form Factor includes alternatives such as QSFP-DD, CFP2, and customized modules addressing ultra-high bandwidth, extended reach, dense port configurations, thermal requirements, and specialized network architectures.
Based on Type, the market is segmented into 25G, 100G, 50G, 400G, and 200G. 25G remains important for radio access, small-cell, and incremental network upgrades, while 50G provides an intermediate capacity option for operators moving beyond established lower-speed links. 100G supports aggregation, metro, macro-cell backhaul, enterprise networks, and edge-cloud connectivity where higher traffic concentration requires greater bandwidth.
200G addresses specialized high-capacity transport and data-intensive applications, while 400G is increasingly deployed across advanced aggregation, core transport, hyperscale data centers, and edge-cloud infrastructure. Silicon photonics, coherent technologies, advanced modulation, and AI-driven data-center expansion are strengthening migration toward higher-speed optical connectivity.
Free Valuable Insights: The Global 5G Optical Transceiver Market will hit USD 17244.9 Million billion by 2033, at a CAGR of 24.3%
Based on Country, the market is segmented into US, Canada, Mexico, and Rest of North America. The US market dominated the North America 5G Optical Transceiver Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 3.6 billion by 2032, growing at a CAGR of 22.7 % during the forecast period. The Canada market is expected to witness a CAGR of 26.9% during (2026 - 2033). Additionally, The Mexico market is expected to witness a CAGR of 25.8% during (2026 - 2033).
Across North America, 5G optical transceiver adoption is being shaped by higher data rates, photonic integration, network densification, energy efficiency, and increasingly resilient supply chains. The US emphasizes 400G and emerging 800G connectivity, coherent optics, silicon photonics, co-packaged optics, ribbon fiber, AI-oriented data centers, and localized supply chains, while Canada focuses on silicon photonics, coherent technologies, energy-efficient modules, edge computing, and scalable fiber infrastructure. Mexico is advancing coherent optics, compact low-power designs, localization, photonic integration, and tailored urban and rural deployments, whereas Rest of North America continues to develop higher-speed transceivers, interoperable modular designs, low-power architectures, advanced diagnostics, and localized optical network solutions.
By Infrastructure
By Distance
By Wavelength
By Form Factor
By Type
By Country
Set to reach $4.5 Billion by 2032, growing at 23.4% CAGR during 2026-2033.
The US leads with $3.6 billion by 2032, growing at a CAGR of 22.7% during 2026-2033.
Rising demand for 5G Fronthaul, reaching $3.3 billion by 2032 at a 23.2% CAGR during 2026-2033.
Expected to reach $3.3 billion by 2032, growing at a 23.2% CAGR during 2026-2033.
Canada is expected to witness a CAGR of 26.9% during 2026-2033.
The 1 to 10 Km market is expected to witness highest CAGR of 24% during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.

 Unique Offerings