The sample copy of this report is available for access.
The Asia Pacific Electronic Design Automation Software Market is expected to reach USD 8.7 billion by 2030, growing at a CAGR of 10.1% during (2026 - 2033).
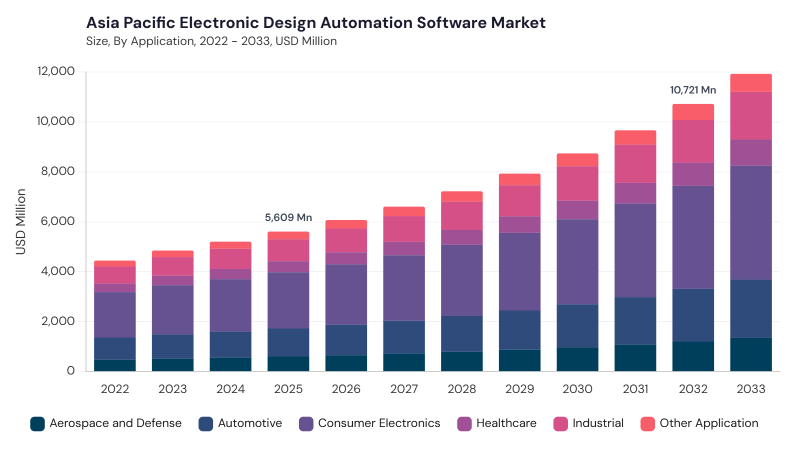
The Asia Pacific Electronic Design Automation Software Market evolved from basic computer-aided circuit schematic and layout tools into advanced platforms supporting simulation, verification, synthesis, physical design, and system-level automation. Rising semiconductor complexity and expanding fabrication capabilities across major regional technology hubs accelerated adoption of increasingly scalable design environments. Integration of hardware description languages and automated synthesis transformed manual workflows into software-driven processes, while advanced packaging, heterogeneous integration, and system-on-chip architectures widened design requirements. Current platforms increasingly incorporate artificial intelligence, cloud computing, hardware-software co-design, advanced analytics, and multi-domain design capabilities.
AI-driven automation, semiconductor ecosystem expansion, cloud-based collaboration, and support for emerging chip architectures are shaping current market development. Machine learning is increasingly used for design optimization, error detection, verification, predictive analysis, and design-space exploration, helping engineering teams address growing chip complexity. Expansion of advanced semiconductor manufacturing, heterogeneous integration, AI accelerators, IoT devices, and software-defined systems is strengthening demand for integrated EDA platforms. Cloud environments are also improving scalable computing and distributed collaboration, while security, export controls, intellectual-property protection, interoperability, and localized semiconductor initiatives continue to influence market strategies across the region.
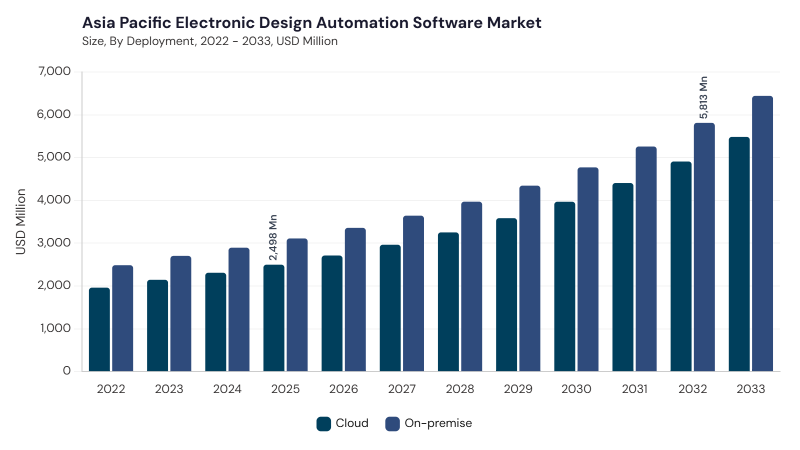
Based on Deployment, the market is segmented into On-premise and Cloud. The On-premise market dominated the Asia Pacific Electronic Design Automation Software Market by Deployment in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 4.7 billion by 2030, growing at a CAGR of 9.8 % during the forecast period. The Cloud market is expected to witness a CAGR of 10.6% during (2026 - 2033).
On-premise deployment supports semiconductor design houses, electronics manufacturers, OEMs, and research organizations requiring internally controlled infrastructure, customized environments, and high-performance computing for verification, synthesis, and physical design. Cloud deployment provides scalable computing, remote accessibility, collaborative engineering, and reduced upfront infrastructure requirements, making it increasingly relevant for startups, fabless semiconductor companies, and distributed teams. Growing cloud infrastructure, SaaS adoption, encryption, AI-integrated platforms, and hybrid deployment models are broadening cloud adoption while addressing regional security and compliance concerns.
Based on End-use, the market is segmented into Microprocessors & Controllers, Memory Management Unit (MMU), and Other End-use. The Microprocessors & Controllers market dominated the Asia Pacific Electronic Design Automation Software Market by End-use in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 6.0 billion by 2030, growing at a CAGR of 9.8 % during the forecast period. The Memory Management Unit (MMU) market is expected to witness a CAGR of 10.5% during (2026 - 2033). The Other End-use market is expected to witness a CAGR of 11.4% during (2026 - 2033).
Microprocessors & Controllers require advanced verification, low-power optimization, system-on-chip development, hardware-software co-design, and scalable simulation capabilities for smartphones, vehicles, industrial systems, connected devices, and embedded applications. Memory Management Unit applications depend on EDA platforms for memory translation, protection, cache management, virtualization, and processor-memory integration across AI accelerators, mobile chipsets, servers, and high-performance computing. Other End-use includes telecommunications hardware, custom computing architectures, semiconductor research, networking devices, quantum technologies, specialized processors, and emerging advanced-packaging applications.
Based on Product, the market is segmented into Computer-aided Engineering (CAE), Semiconductor Intellectual Property (SIP), IC Physical Design and Verification, Printed Circuit Board and Multi-chip Module (PCB and MCM), and Services. Computer-aided Engineering supports circuit simulation, power analysis, signal integrity, thermal modeling, and system-level validation before physical implementation. Semiconductor Intellectual Property enables reuse of processor cores, memory controllers, interfaces, and other verified functional blocks within increasingly complex system-on-chip architectures.
IC Physical Design and Verification supports floorplanning, placement, routing, timing analysis, design-rule checking, and manufacturability requirements for advanced semiconductor nodes. PCB and MCM tools address board design, signal integrity, electromagnetic compatibility, thermal management, advanced packaging, and heterogeneous integration, while Services include consulting, customization, integration, maintenance, training, workflow automation, and cloud migration support.
Based on Application, the market is segmented into Consumer Electronics, Automotive, Industrial, Aerospace and Defense, Healthcare, and Other Application. Consumer Electronics relies on EDA software for rapid product cycles, low-power design, high-density integration, AI acceleration, connectivity, and system-on-chip development. Automotive applications require rigorous verification for electric vehicles, advanced driver-assistance systems, autonomous driving, connected cars, functional safety, and power-management electronics.
Industrial applications include robotics, smart factories, industrial IoT, automation, and power systems, while Aerospace and Defense requires secure and highly reliable design workflows for avionics, radar, satellite communications, and military electronics. Healthcare applications support medical devices, diagnostics, wearable health monitors, and connected healthcare systems, while Other Application includes telecommunications, energy systems, smart appliances, quantum electronics, and other specialized design environments.
Free Valuable Insights: Electronic Design Automation Software Market is Predicted to reach USD 35.9 Billion billion by 2033, at a CAGR of 9.6%
Based on Country, the market is segmented into China, Japan, India, South Korea, Singapore, Malaysia, and Rest of Asia Pacific. The China market dominated the Asia Pacific Electronic Design Automation Software Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 2.8 billion by 2030, growing at a CAGR of 8.5 % during the forecast period. The Japan market is expected to witness a CAGR of 8.9% during (2026 - 2033). Additionally, The India market is expected to witness a CAGR of 11.4% during (2026 - 2033).
Across Asia Pacific, EDA software adoption is being shaped by AI integration, semiconductor localization, cloud computing, advanced packaging, and increasingly complex chip architectures. China emphasizes indigenous EDA development, AI-assisted automation, hardware verification, localization, and reduced dependence on restricted foreign technologies, while Japan focuses on AI-enabled design, chiplet architectures, 3D IC integration, digital transformation, and cloud-native workflows. India is advancing AI-assisted automation, cloud-based EDA, software-defined systems, photonics integration, and domestic semiconductor capabilities, whereas South Korea emphasizes AI-driven manufacturing, smart factories, secure design, and localized semiconductor infrastructure. Singapore focuses on AI-enhanced automation, localized innovation ecosystems, cloud platforms, workforce development, and advanced-node integration, while Malaysia emphasizes AI-enabled design, cloud adoption, local customization, training, and semiconductor ecosystem development. Rest of Asia Pacific continues to develop AI-driven workflows, digitalized services, localized EDA platforms, SaaS models, cloud infrastructure, interoperability, and region-specific semiconductor design capabilities.
By Deployment
By End-use
By Product
By Application
By Country
Set to reach $8.7 Billion by 2030, growing at 10.1% CAGR during 2026-2033.
China leads with a market value of $2.8 billion by 2030, growing at an 8.5% CAGR during 2026-2033.
Rising demand for microprocessors and controllers, reaching $6.0 billion by 2030 at a 9.8% CAGR during 2026-2033.
The On-premise segment will achieve $4.7 billion by 2030, growing at a 9.8% CAGR during 2026-2033.
The India market is expected to witness an 11.4% CAGR during 2026-2033.
The Cloud market is expected to witness a 10.6% CAGR during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.

 Unique Offerings