The sample copy of this report is available for access.
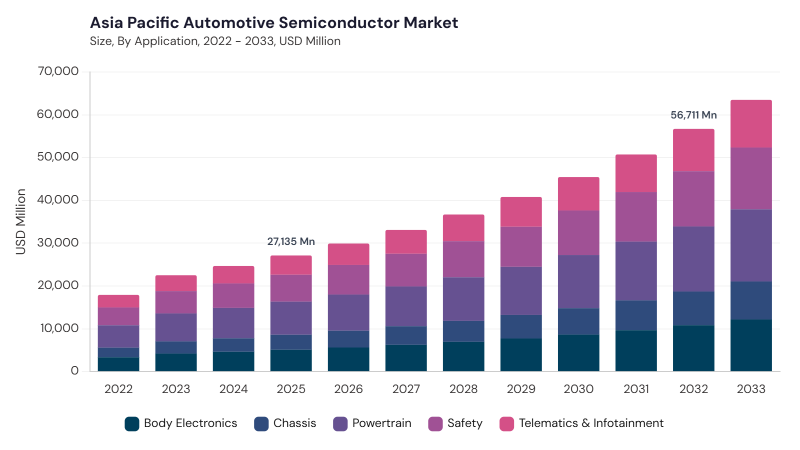
The Asia Pacific Automotive Semiconductor Market is expected to reach USD 45.4 billion by 2030, growing at a CAGR of 11.3% during (2026 - 2033).
The Asia Pacific Automotive Semiconductor Market evolved from basic electronic components supporting engine control and power management into a highly integrated ecosystem serving electrification, autonomous driving, connectivity, and software-defined vehicles. Early development benefited from strong semiconductor manufacturing capabilities across Japan, South Korea, Taiwan, and other regional hubs, while subsequent advances expanded semiconductor use into ADAS, infotainment, sensing, and advanced power electronics. Increasing localization of fabrication, assembly, testing, and design capabilities further strengthened regional supply chains. Current development increasingly emphasizes AI-enabled processors, wide-bandgap power devices, centralized computing, advanced sensors, and automotive-grade semiconductor platforms supporting intelligent and electric mobility.
Electric vehicle production, AI integration, vehicle connectivity, supply chain localization, and advanced safety technologies are shaping current market development. Semiconductor suppliers are increasingly advancing SiC and GaN power devices for electric drivetrains, high-performance processors and neural accelerators for ADAS, and communication ICs supporting 5G, V2X, and connected vehicle services. Expanding regional fabrication and packaging capacity is strengthening supply resilience while enabling closer integration with major automotive manufacturing clusters. At the same time, high fabrication costs, geopolitical tensions, trade restrictions, skilled workforce shortages, cybersecurity requirements, automotive qualification standards, and increasingly complex vehicle architectures continue to influence investment and technology deployment.
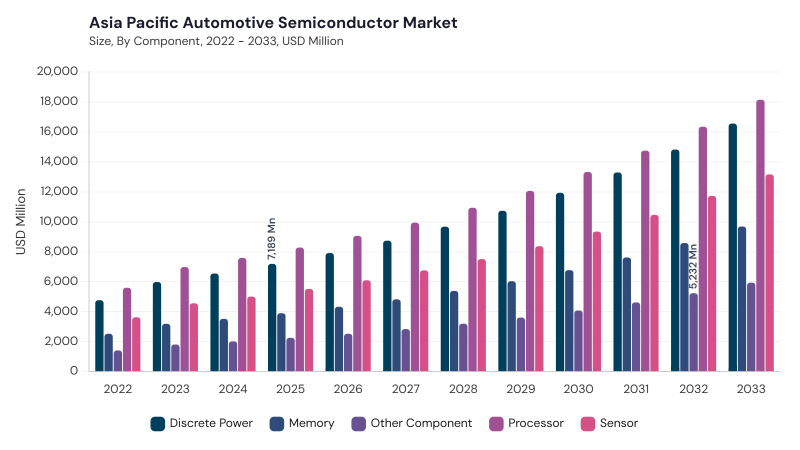
Based on Component, the market is segmented into Processor, Discrete Power, Sensor, Memory, and Other Component. The Processor market dominated the Asia Pacific Automotive Semiconductor Market by Component in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 13.3 billion by 2030, growing at a CAGR of 10.4 % during the forecast period. The Discrete Power market is expected to witness a CAGR of 11.1% during (2026 - 2033). The Other Component market is expected to witness a CAGR of 13% during (2026 - 2033).
Processor semiconductors include microcontrollers, CPUs, ASICs, and system-on-chip platforms supporting powertrain control, infotainment, ADAS, connectivity, and AI-enabled vehicle functions. Discrete Power includes MOSFETs, IGBTs, diodes, SiC, and GaN devices used in electric drivetrains, battery systems, inverters, and charging applications. Sensor includes radar, lidar, imaging, environmental, temperature, pressure, and positioning technologies supporting safety and automation. Memory enables software, navigation, infotainment, data processing, and over-the-air functionality, while Other Component includes power-management ICs, analog devices, motor drivers, interfaces, and communication chips supporting integrated vehicle electronics.
Based on Application, the market is segmented into Powertrain, Safety, Body Electronics, Telematics & Infotainment, and Chassis. The Powertrain market dominated the Asia Pacific Automotive Semiconductor Market by Application in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 12.4 billion by 2030, growing at a CAGR of 10.4 % during the forecast period. The Safety market is expected to witness a CAGR of 11.1% during (2026 - 2033). Additionally, The Body Electronics market is expected to witness highest CAGR of 11.7% during (2026 - 2033).
Powertrain applications use power semiconductors, microcontrollers, battery-management ICs, sensors, and advanced control devices across combustion, hybrid, and electric propulsion systems. Safety applications rely on processors, radar, lidar, cameras, and sensor-fusion platforms for ADAS, collision avoidance, driver monitoring, and active safety. Body Electronics covers smart lighting, climate control, access systems, cabin automation, and convenience functions, while Telematics & Infotainment supports digital cockpits, navigation, connectivity, multimedia, V2X, and over-the-air services. Chassis applications include electronic steering, braking, suspension, traction, and stability-control systems requiring reliable real-time semiconductor operation.
Based on Vehicle Type, the market is segmented into Passenger Vehicle, Light Commercial Vehicle, and Heavy Commercial Vehicle. Passenger Vehicles require extensive semiconductor integration across powertrain, battery management, ADAS, connectivity, infotainment, sensing, and centralized computing systems. Light Commercial Vehicles increasingly use semiconductors for fleet telematics, electric drivetrains, battery management, emission control, connected logistics, and driver-assistance technologies supporting urban delivery operations.
Heavy Commercial Vehicles rely on durable semiconductor solutions for powertrain control, electronic braking, fleet telematics, predictive maintenance, safety systems, and gradual electrification. Across all vehicle categories, semiconductor adoption is increasingly influenced by reliability, cost efficiency, regulatory compliance, and connectivity requirements.
Free Valuable Insights: Automotive Semiconductor Market is Predicted to reach USD 138.1 Billion billion by 2033, at a CAGR of 11.1%
Based on Country, the market is segmented into China, Japan, India, South Korea, Singapore, Malaysia, and Rest of Asia Pacific. The China market dominated the Asia Pacific Automotive Semiconductor Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 18.1 billion by 2030, growing at a CAGR of 10 % during the forecast period. The Japan market is expected to witness a CAGR of 10.5% during (2026 - 2033). Additionally, The India market is expected to witness a CAGR of 12.5% during (2026 - 2033).
Across Asia Pacific, automotive semiconductor adoption is being shaped by electrification, AI-enabled mobility, semiconductor localization, connectivity, and supply chain resilience. China emphasizes EV power devices, AI-capable chips, domestic semiconductor manufacturing, ADAS, and reduced import dependency, while Japan focuses on SiC and GaN technologies, autonomous-driving processors, functional safety, and localized supply networks. India is advancing EV power semiconductors, domestic manufacturing, connected vehicles, sensor integration, and cost-effective localized solutions, whereas South Korea emphasizes EV electronics, ADAS, smart infotainment, advanced manufacturing, and supply chain localization. Singapore focuses on high-performance automotive chips, AI processing, advanced fabrication, testing, and resilient regional supply chains, while Malaysia emphasizes power semiconductors, ADAS, V2X, local manufacturing, advanced packaging, and testing capabilities. Rest of Asia Pacific continues to develop EV-oriented power electronics, connected vehicle chips, localized production, advanced sensors, and semiconductor platforms supporting autonomous and intelligent mobility.
By Component
By Application
By Vehicle Type
By Country
Set to reach $45.4 Billion by 2030, growing at 11.3% CAGR during 2026-2033.
China leads with a market value of USD 18.1 billion by 2030, growing at a CAGR of 10% during the forecast period.
Rising demand for processors, reaching USD 13.3 billion by 2030, growing at a 10.4% CAGR during 2026-2033.
Powertrain segment to reach USD 12.4 billion by 2030, growing at a 10.4% CAGR during the forecast period.
The India market is expected to witness a CAGR of 12.5% during 2026-2033.
Body electronics segment is expected to witness the highest CAGR of 11.7% during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.

 Unique Offerings