The sample copy of this report is available for access.
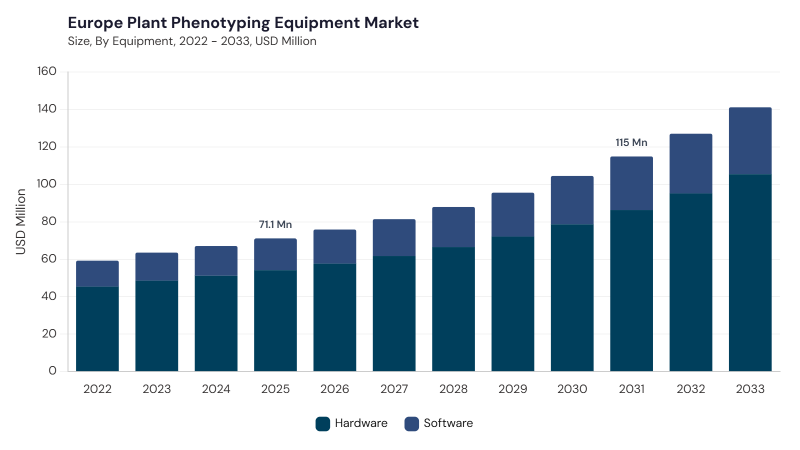
The Europe Plant Phenotyping Equipment Market is expected to reach USD 114.8 million by 2031, growing at a CAGR of 9.3% during (2026 - 2033).
The Europe Plant Phenotyping Equipment Market evolved from manual plant-trait observation and basic measurement techniques toward automated, high-throughput platforms capable of precise and non-destructive analysis. Advances in multispectral, hyperspectral, 3D imaging, environmental sensing, robotics, and automated data acquisition progressively expanded the scale and accuracy of phenotypic assessment. Integration of machine learning and advanced analytics further transformed raw plant observations into actionable genotype-to-phenotype insights. Current development increasingly combines sophisticated sensing hardware, AI-enabled software, cloud-based data management, multi-omics integration, and field-deployable systems to support climate-resilient breeding, sustainable agriculture, and precision crop research.
High-throughput phenotyping, multi-sensor fusion, AI-driven analytics, data interoperability, and sustainability-focused crop research are shaping current market development. European research institutions, breeding organizations, universities, and agricultural technology stakeholders increasingly use UAVs, robotic platforms, spectral imaging, environmental sensors, cloud analytics, and machine learning to evaluate complex plant traits efficiently. Growing emphasis on climate resilience, precision agriculture, genomic technologies, resource-use efficiency, and standardized phenotypic data is broadening equipment adoption. However, high capital and operating costs, regulatory complexity, limited standardization, interoperability constraints, data-management requirements, and shortages of specialized technical expertise continue to influence deployment.
Based on Equipment, the market is segmented into Hardware and Software. The Hardware market dominated the Europe Plant Phenotyping Equipment Market by Equipment in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 86.2 million by 2031, growing at a CAGR of 9 % during the forecast period. The Software market is expected to witness a CAGR of 10.1% during (2026 - 2033).
Hardware provides the physical foundation for plant-trait measurement through imaging systems, multispectral and hyperspectral sensors, cameras, robotic platforms, automated greenhouse systems, portable field instruments, and environmental monitoring devices. These technologies support measurement of plant morphology, physiology, growth, stress responses, and environmental interactions across laboratory, greenhouse, and field environments. Software enables image processing, trait extraction, statistical analysis, visualization, data organization, and comparison of experimental results. Increasing integration of computer vision, AI, machine learning, cloud platforms, and standardized data-management tools is strengthening software's role in converting complex sensor outputs into reproducible phenotypic insights.
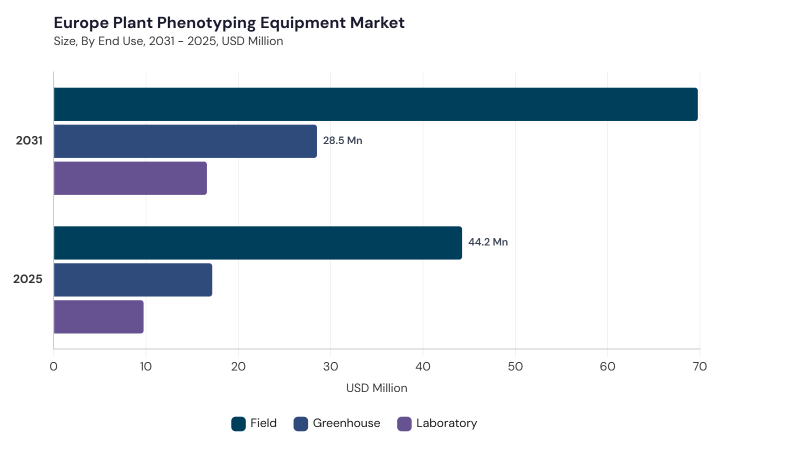
Based on End Use, the market is segmented into Field, Greenhouse, and Laboratory. The Field market dominated the Europe Plant Phenotyping Equipment Market by End Use in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 69.7 million by 2031, growing at a CAGR of 8.8 % during the forecast period. The Greenhouse market is expected to witness a CAGR of 9.8% during (2026 - 2033). Additionally, The Laboratory market is expected to witness highest CAGR of 10.2% during (2026 - 2033).
Field phenotyping uses UAV imaging, remote sensing, automated field vehicles, mobile platforms, geospatial analytics, and spectral sensors to evaluate plant performance under real-world conditions. Greenhouse phenotyping provides controlled environments for studying responses to temperature, humidity, light, water, nutrients, and stress through automated imaging, robotics, and integrated sensing systems. Laboratory phenotyping supports detailed physiological, biochemical, cellular, and genetic investigation using microscopy, spectroscopy, imaging, and other specialized analytical technologies. Together, these environments enable researchers to connect highly controlled plant analysis with practical crop performance and broader breeding objectives.
Based on Application, the market is segmented into Quality Assessment, Plant Research, Breeding, and Product Development. Quality Assessment uses automated imaging, spectral sensors, fluorescence technologies, and data-analysis tools to evaluate plant height, biomass, chlorophyll content, stress indicators, physiological condition, and phenotypic consistency. Plant Research supports investigation of plant development, biodiversity, environmental responses, disease interactions, and genotype-environment relationships using controlled and field-based platforms.
Breeding applies high-throughput sensors, drones, LiDAR, imaging systems, and analytics to screen large genetic populations and identify resilient, resource-efficient, and agronomically valuable traits. Product Development uses phenotypic validation to evaluate new plant varieties, biostimulants, fertilizers, crop-protection products, and other agricultural innovations under controlled and field conditions.
Free Valuable Insights: The Worldwide Plant Phenotyping Equipment Market is projected to reach USD 596.7 Million billion by 2033, at a CAGR of 9.8%
Based on Country, the market is segmented into Germany, UK, France, Russia, Spain, Italy, and Rest of Europe. The Germany market dominated the Europe Plant Phenotyping Equipment Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 23.3 million by 2031, growing at a CAGR of 7.8 % during the forecast period. The UK market is expected to witness a CAGR of 8.2% during (2026 - 2033). Additionally, The France market is expected to witness a CAGR of 10% during (2026 - 2033).
Across Europe, plant phenotyping adoption is being shaped by automation, AI, advanced imaging, climate-resilient crop research, and increasingly integrated data environments. Germany emphasizes AI, robotic phenotyping, multi-sensor platforms, multi-omics integration, and collaborative research infrastructure, while the UK focuses on AI-enabled analysis, field-deployable LiDAR, high-resolution sensing, national phenotyping networks, and scalable research platforms. France is advancing multi-source data integration, automated high-throughput systems, sustainability-focused phenotyping, and predictive analytics, whereas Russia emphasizes precision agriculture, IoT, digital twins, AI-supported analysis, and modular sensor platforms. Spain focuses on machine learning, multi-environment field phenotyping, portable sensor systems, standardized data practices, and sustainable equipment design, while Italy emphasizes multi-sensor imaging, AI analytics, water-use efficiency, controlled-environment phenotyping, and harmonized data standards. Rest of Europe continues to develop non-invasive sensing, robotics, cloud-based data management, AI-supported analytics, collaborative infrastructure, and scalable platforms adapted to diverse crops and research environments.
By Equipment
By End Use
By Application
By Country
Set to reach $114.8 Million by 2031, growing at 9.3% CAGR during 2026-2033.
Germany leads with $23.3 million by 2031, growing at 7.8% CAGR during the forecast period.
Hardware segment will reach $86.2 million by 2031, growing at 9% CAGR during 2026-2033.
Field segment will achieve $69.7 million by 2031, growing at 8.8% CAGR during 2026-2033.
The UK market is expected to witness a CAGR of 8.2% during 2026-2033.
Software segment is expected to witness a CAGR of 10.1% during 2026-2033.
Our team of dedicated experts can provide you with attractive expansion opportunities for your business.

 Unique Offerings