North America Data Center Accelerator Market Size, Share & Industry Analysis Report By Type (Cloud, and HPC), By Application (Deep Learning Training, and Public Cloud Interface), By Processor (GPU, and FPGA), By Country Outlook and Forecast, 2026 - 2033
Published Date : 25-Oct-2026 |
Pages: 173 |
Report Format: PDF + Excel |
COVID-19 Impact on the North America Data Center Accelerator Market
The North America Data Center Accelerator Market is expected to reach USD 37.9 billion by 2032, growing at a CAGR of 24% during (2026 - 2033).
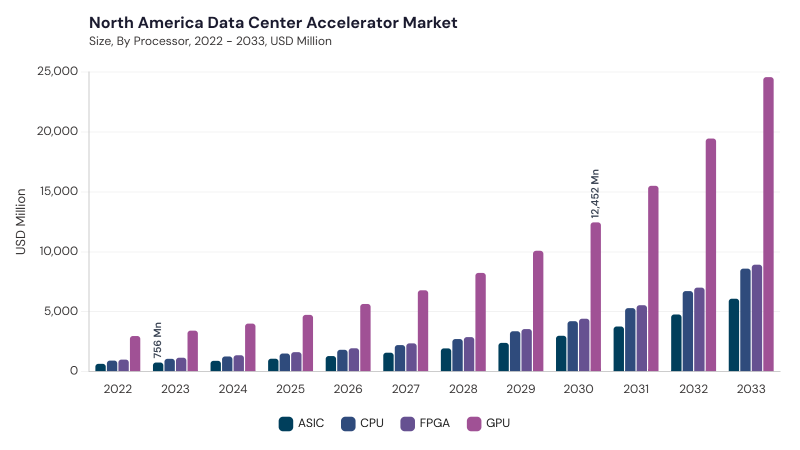
The North America Data Center Accelerator Market evolved from CPU-centric data center architectures toward heterogeneous infrastructure built around GPUs, FPGAs, ASICs, CPUs, high-bandwidth memory, advanced networking, and specialized software. Early adoption was concentrated in HPC, scientific laboratories, engineering simulations, graphics processing, and research workloads, where accelerators improved parallel computing performance. Hyperscale cloud growth shifted accelerators into commercial data center infrastructure, while machine learning and generative AI made them strategic for large-scale model training, inference, analytics, and cloud computing. The market now supports AI development, enterprise workloads, scientific computing, and high-density data center operations.
Rack-scale accelerated computing, custom AI silicon, power efficiency, and infrastructure availability are shaping current market development. Large AI models require coordinated accelerator clusters supported by memory, networking, cooling, storage, and software rather than isolated processors. Hyperscale providers are also increasing interest in custom ASICs to improve cost, performance, energy efficiency, and workload optimization. Accelerator purchasing is therefore influenced by performance-per-watt, rack density, memory bandwidth, interconnect scalability, processor availability, and total cost of ownership. However, high capital expenditure, power constraints, cooling requirements, manufacturing dependency, rapid product cycles, and software compatibility remain key adoption challenges.
Type Outlook
Based on Type, the market is segmented into Cloud and HPC. The Cloud market dominated the North America Data Center Accelerator Market by Type in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 23.3 billion by 2032, growing at a CAGR of 23.6 % during the forecast period. The HPC market is expected to witness a CAGR of 24.6% during (2026 - 2033).
Cloud platforms allow enterprises, startups, developers, public-sector users, and research organizations to access GPUs and other accelerators without building dedicated infrastructure. This model converts major capital investment into flexible consumption while supporting training, inference, analytics, and HPC workloads. HPC maintained a promising presence due to demand from laboratories, universities, aerospace, defense, pharmaceuticals, energy, engineering, and scientific research. As AI and HPC converge, both environments increasingly require high-performance processors, HBM, advanced interconnects, liquid cooling, and mature software ecosystems.
Application Outlook
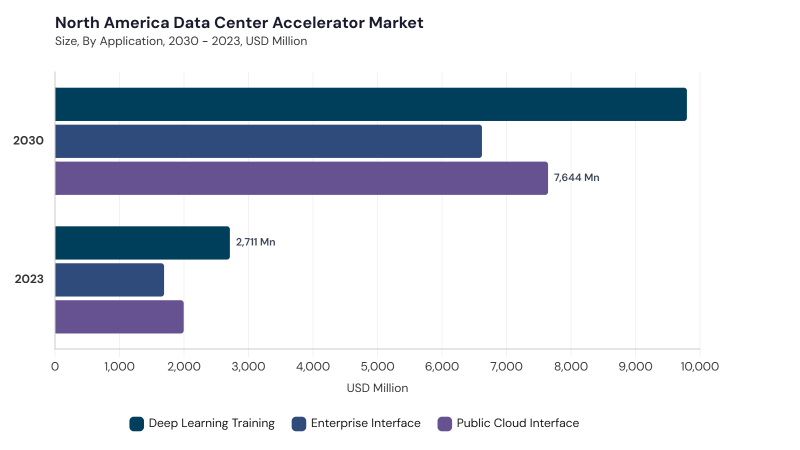
Based on Application, the market is segmented into Deep Learning Training, Public Cloud Interface, and Enterprise Interface. Deep Learning Training requires massive accelerator clusters, high memory bandwidth, faster interconnects, distributed-training software, and strong cluster utilization to process large datasets and complex AI models. Public Cloud Interface holds a significant position as organizations use accelerator-enabled cloud instances, managed AI services, containers, and scalable compute resources to avoid direct ownership of expensive hardware.
Enterprise Interface maintains a promising presence as businesses deploy private, hybrid, or managed accelerator infrastructure for AI, analytics, cybersecurity, automation, fraud detection, engineering, and industry-specific workloads. Growth across all applications is supported by wider commercialization of generative AI and accelerated computing.
Processor Outlook
Based on Processor, the market is segmented into GPU, FPGA, CPU, and ASIC. GPUs remain central because their parallel architecture, HBM capacity, memory bandwidth, AI processing capability, and high-speed interconnects support large AI and HPC clusters. FPGA garnered a substantial share due to reprogrammability, low-latency performance, and suitability for networking, inference, storage acceleration, cybersecurity, and specialized data processing.
CPU retained a considerable role as the host and orchestration layer for operating systems, workload scheduling, databases, networking, and heterogeneous computing. ASIC represented a promising segment as hyperscalers and large technology companies pursue custom silicon for predictable AI workloads, improved efficiency, and better performance-per-watt.
Free Valuable Insights: The Global Data Center Accelerator Market will hit USD 137.0 Billion billion by 2033, at a CAGR of 24.8%
Country Outlook
Based on Country, the market is segmented into US, Canada, Mexico, and Rest of North America. The US market dominated the North America Data Center Accelerator Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 28.8 billion by 2032, growing at a CAGR of 23.2 % during the forecast period. The Canada market is expected to witness a CAGR of 26.6% during (2026 - 2033). Additionally, The Mexico market is expected to witness a CAGR of 26.1% during (2026 - 2033).
Across North America, data center accelerator adoption varies with AI infrastructure scale, cloud maturity, research computing, enterprise digitalization, power availability, and data center investment. The US remains the central demand and innovation hub, supported by hyperscale AI clusters, semiconductor design, generative AI development, custom silicon, energy planning, and integrated accelerator ecosystems. Canada focuses on AI research, cloud infrastructure, energy-efficient computing, data governance, domestic computing capacity, and regional accelerator access. Mexico is advancing through cloud services, manufacturing digitalization, nearshoring-linked analytics, industrial automation, enterprise AI, and regional data center expansion. Rest of North America remains smaller but benefits from cloud-delivered accelerators, managed AI services, scientific computing, cybersecurity, enterprise analytics, and service-layer integration.
List of Key Companies Profiled
- NVIDIA Corporation
- Broadcom
- Advanced Micro Devices
- Marvell
- Huawei Technologies
- Altera
- Intel
- Cerebras Systems
- Cambricon Technologies
- Groq
North America Data Center Accelerator Market Report Segmentation
By Type
- Cloud
- HPC
By Application
- Deep Learning Training
- Public Cloud Interface
- Enterprise Interface
By Processor
- GPU
- FPGA
- CPU
- ASIC
By Country
- US
- Canada
- Mexico
- Rest of North America
1.1 Market Overview
1.2 Key Factors Impacting Market
1.2.1 Market Drivers
1.2.2 Market Restraints
1.2.3 Market Opportunities
1.2.4 Market Challenges
1.2.5 Market Trends
1.2.6 State of Competition
1.2.7 Market Consolidation
1.2.8 Key Customer Criteria
1.3 Product Life Cycle
1.4 Segmentation By Type
1.4.1 Cloud
1.4.2 HPC
1.5 Segmentation By Application
1.5.1 Deep Learning Training
1.5.2 Public Cloud Interface
1.5.3 Enterprise Interface
1.6 Segmentation By Processor
1.6.1 GPU
1.6.2 FPGA
1.6.3 CPU
1.6.4 ASIC
1.7 Segmentation By Country
1.7.1 US
1.7.1.1 Segmentation By Type
1.7.1.1.1 Cloud
1.7.1.1.2 HPC
1.7.1.2 Segmentation By Application
1.7.1.2.1 Deep Learning Training
1.7.1.2.2 Public Cloud Interface
1.7.1.2.3 Enterprise Interface
1.7.1.3 Segmentation By Processor
1.7.1.3.1 GPU
1.7.1.3.2 FPGA
1.7.1.3.3 CPU
1.7.1.3.4 ASIC
1.7.2 Canada
1.7.2.1 Segmentation By Type
1.7.2.1.1 Cloud
1.7.2.1.2 HPC
1.7.2.2 Segmentation By Application
1.7.2.2.1 Deep Learning Training
1.7.2.2.2 Public Cloud Interface
1.7.2.2.3 Enterprise Interface
1.7.2.3 Segmentation By Processor
1.7.2.3.1 GPU
1.7.2.3.2 FPGA
1.7.2.3.3 CPU
1.7.2.3.4 ASIC
1.7.3 Mexico
1.7.3.1 Segmentation By Type
1.7.3.1.1 Cloud
1.7.3.1.2 HPC
1.7.3.2 Segmentation By Application
1.7.3.2.1 Deep Learning Training
1.7.3.2.2 Public Cloud Interface
1.7.3.2.3 Enterprise Interface
1.7.3.3 Segmentation By Processor
1.7.3.3.1 GPU
1.7.3.3.2 FPGA
1.7.3.3.3 CPU
1.7.3.3.4 ASIC
1.7.4 Rest of North America
1.7.4.1 Segmentation By Type
1.7.4.1.1 Cloud
1.7.4.1.2 HPC
1.7.4.2 Segmentation By Application
1.7.4.2.1 Deep Learning Training
1.7.4.2.2 Public Cloud Interface
1.7.4.2.3 Enterprise Interface
1.7.4.3 Segmentation By Processor
1.7.4.3.1 GPU
1.7.4.3.2 FPGA
1.7.4.3.3 CPU
1.7.4.3.4 ASIC
Chapter 2. Company Snapshots
2.1 NVIDIA Corporation
2.1.1 Business Overview
2.1.2 Key Information
2.1.3 Company Focus on Data Center Accelerator Market
2.1.4 Strategic Insights
2.1.5 Strategy Deployed
2.1.6 Product & Service Portfolio
2.1.7 Capability Overview
2.1.8 Technology & Innovation Focus
2.1.9 SWOT Analysis
2.1.10 Customers / End Users
2.1.11 Competitive Positioning
2.1.12 Key Differentiators
2.1.13 Portfolio Matrix
2.1.14 Future Outlook
2.2 Broadcom
2.2.1 Business Overview
2.2.2 Key Information
2.2.3 Company Focus on Data Center Accelerator Market
2.2.4 Strategic Insights
2.2.5 Strategy Deployed
2.2.6 Product & Service Portfolio
2.2.7 Capability Overview
2.2.8 Technology & Innovation Focus
2.2.9 SWOT Analysis
2.2.10 Customers / End Users
2.2.11 Competitive Positioning
2.2.12 Key Differentiators
2.2.13 Portfolio Matrix
2.2.14 Future Outlook
2.3 Advanced Micro Devices
2.3.1 Business Overview
2.3.2 Key Information
2.3.3 Company Focus on Data Center Accelerator Market
2.3.4 Strategic Insights
2.3.5 Strategy Deployed
2.3.6 Product & Service Portfolio
2.3.7 Capability Overview
2.3.8 Technology & Innovation Focus
2.3.9 SWOT Analysis
2.3.10 Customers / End Users
2.3.11 Competitive Positioning
2.3.12 Key Differentiators
2.3.13 Portfolio Matrix
2.3.14 Future Outlook
2.4 Marvell
2.4.1 Business Overview
2.4.2 Key Information
2.4.3 Company Focus on Data Center Accelerator Market
2.4.4 Strategic Insights
2.4.5 Strategy Deployed
2.4.6 Product & Service Portfolio
2.4.7 Capability Overview
2.4.8 Technology & Innovation Focus
2.4.9 SWOT Analysis
2.4.10 Customers / End Users
2.4.11 Competitive Positioning
2.4.12 Key Differentiators
2.4.13 Portfolio Matrix
2.4.14 Future Outlook
2.5 Huawei Technologies
2.5.1 Business Overview
2.5.2 Key Information
2.5.3 Company Focus on Data Center Accelerator Market
2.5.4 Strategic Insights
2.5.5 Strategy Deployed
2.5.6 Product & Service Portfolio
2.5.7 Capability Overview
2.5.8 Technology & Innovation Focus
2.5.9 SWOT Analysis
2.5.10 Customers / End Users
2.5.11 Competitive Positioning
2.5.12 Key Differentiators
2.5.13 Portfolio Matrix
2.5.14 Future Outlook
2.6 Altera
2.6.1 Business Overview
2.6.2 Key Information
2.6.3 Company Focus on Data Center Accelerator Market
2.6.4 Strategic Insights
2.6.5 Strategy Deployed
2.6.6 Product & Service Portfolio
2.6.7 Capability Overview
2.6.8 Technology & Innovation Focus
2.6.9 SWOT Analysis
2.6.10 Customers / End Users
2.6.11 Competitive Positioning
2.6.12 Key Differentiators
2.6.13 Portfolio Matrix
2.6.14 Future Outlook
2.7 Intel
2.7.1 Business Overview
2.7.2 Key Information
2.7.3 Company Focus on Data Center Accelerator Market
2.7.4 Strategic Insights
2.7.5 Strategy Deployed
2.7.6 Product & Service Portfolio
2.7.7 Capability Overview
2.7.8 Technology & Innovation Focus
2.7.9 SWOT Analysis
2.7.10 Customers / End Users
2.7.11 Competitive Positioning
2.7.12 Key Differentiators
2.7.13 Portfolio Matrix
2.7.14 Future Outlook
2.8 Cerebras Systems
2.8.1 Business Overview
2.8.2 Key Information
2.8.3 Company Focus on Data Center Accelerator Market
2.8.4 Strategic Insights
2.8.5 Strategy Deployed
2.8.6 Product & Service Portfolio
2.8.7 Capability Overview
2.8.8 Technology & Innovation Focus
2.8.9 SWOT Analysis
2.8.10 Customers / End Users
2.8.11 Competitive Positioning
2.8.12 Key Differentiators
2.8.13 Portfolio Matrix
2.8.14 Future Outlook
2.9 Cambricon Technologies
2.9.1 Business Overview
2.9.2 Key Information
2.9.3 Company Focus on Data Center Accelerator Market
2.9.4 Strategic Insights
2.9.5 Strategy Deployed
2.9.6 Product & Service Portfolio
2.9.7 Capability Overview
2.9.8 Technology & Innovation Focus
2.9.9 SWOT Analysis
2.9.10 Customers / End Users
2.9.11 Competitive Positioning
2.9.12 Key Differentiators
2.9.13 Portfolio Matrix
2.9.14 Future Outlook
2.10 Groq
2.10.1 Business Overview
2.10.2 Key Information
2.10.3 Company Focus on Data Center Accelerator Market
2.10.4 Strategic Insights
2.10.5 Strategy Deployed
2.10.6 Product & Service Portfolio
2.10.7 Capability Overview
2.10.8 Technology & Innovation Focus
2.10.9 SWOT Analysis
2.10.10 Customers / End Users
2.10.11 Competitive Positioning
2.10.12 Key Differentiators
2.10.13 Portfolio Matrix
2.10.14 Future Outlook
Table 1 North America Data Center Accelerator Market Market, 2022 - 2033, USD Million
Table 2 North America Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
Table 3 North America Deep Learning Training Market, 2022 - 2033, USD Million
Table 4 North America Enterprise Interface Market, 2022 - 2033, USD Million
Table 5 North America Public Cloud Interface Market, 2022 - 2033, USD Million
Table 6 North America Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
Table 7 North America ASIC Market, 2022 - 2033, USD Million
Table 8 North America CPU Market, 2022 - 2033, USD Million
Table 9 North America FPGA Market, 2022 - 2033, USD Million
Table 10 North America GPU Market, 2022 - 2033, USD Million
Table 11 North America Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
Table 12 North America Cloud Market, 2022 - 2033, USD Million
Table 13 North America HPC Market, 2022 - 2033, USD Million
Table 14 United States Data Center Accelerator Market Market, 2022 - 2033, USD Million
Table 15 United States Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
Table 16 United States Deep Learning Training Market, 2022 - 2033, USD Million
Table 17 United States Enterprise Interface Market, 2022 - 2033, USD Million
Table 18 United States Public Cloud Interface Market, 2022 - 2033, USD Million
Table 19 United States Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
Table 20 United States ASIC Market, 2022 - 2033, USD Million
Table 21 United States CPU Market, 2022 - 2033, USD Million
Table 22 United States FPGA Market, 2022 - 2033, USD Million
Table 23 United States GPU Market, 2022 - 2033, USD Million
Table 24 United States Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
Table 25 United States Cloud Market, 2022 - 2033, USD Million
Table 26 United States HPC Market, 2022 - 2033, USD Million
Table 27 Canada Data Center Accelerator Market Market, 2022 - 2033, USD Million
Table 28 Canada Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
Table 29 Canada Deep Learning Training Market, 2022 - 2033, USD Million
Table 30 Canada Enterprise Interface Market, 2022 - 2033, USD Million
Table 31 Canada Public Cloud Interface Market, 2022 - 2033, USD Million
Table 32 Canada Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
Table 33 Canada ASIC Market, 2022 - 2033, USD Million
Table 34 Canada CPU Market, 2022 - 2033, USD Million
Table 35 Canada FPGA Market, 2022 - 2033, USD Million
Table 36 Canada GPU Market, 2022 - 2033, USD Million
Table 37 Canada Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
Table 38 Canada Cloud Market, 2022 - 2033, USD Million
Table 39 Canada HPC Market, 2022 - 2033, USD Million
Table 40 Mexico Data Center Accelerator Market Market, 2022 - 2033, USD Million
Table 41 Mexico Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
Table 42 Mexico Deep Learning Training Market, 2022 - 2033, USD Million
Table 43 Mexico Enterprise Interface Market, 2022 - 2033, USD Million
Table 44 Mexico Public Cloud Interface Market, 2022 - 2033, USD Million
Table 45 Mexico Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
Table 46 Mexico ASIC Market, 2022 - 2033, USD Million
Table 47 Mexico CPU Market, 2022 - 2033, USD Million
Table 48 Mexico FPGA Market, 2022 - 2033, USD Million
Table 49 Mexico GPU Market, 2022 - 2033, USD Million
Table 50 Mexico Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
Table 51 Mexico Cloud Market, 2022 - 2033, USD Million
Table 52 Mexico HPC Market, 2022 - 2033, USD Million
Table 53 Rest of North America Data Center Accelerator Market Market, 2022 - 2033, USD Million
Table 54 Rest of North America Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
Table 55 Rest of North America Deep Learning Training Market, 2022 - 2033, USD Million
Table 56 Rest of North America Enterprise Interface Market, 2022 - 2033, USD Million
Table 57 Rest of North America Public Cloud Interface Market, 2022 - 2033, USD Million
Table 58 Rest of North America Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
Table 59 Rest of North America ASIC Market, 2022 - 2033, USD Million
Table 60 Rest of North America CPU Market, 2022 - 2033, USD Million
Table 61 Rest of North America FPGA Market, 2022 - 2033, USD Million
Table 62 Rest of North America GPU Market, 2022 - 2033, USD Million
Table 63 Rest of North America Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
Table 64 Rest of North America Cloud Market, 2022 - 2033, USD Million
Table 65 Rest of North America HPC Market, 2022 - 2033, USD Million
List of Figures
FIG 1 Key Factors Impacting Market
FIG 2 Market Consolidation
FIG 3 Key Customer Criteria
FIG 4 Product Life Cycle
FIG 5 North America Data Center Accelerator Market Market, 2022 - 2033, USD Million
FIG 6 North America Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
FIG 7 North America Deep Learning Training Market, 2022 - 2033, USD Million
FIG 8 North America Enterprise Interface Market, 2022 - 2033, USD Million
FIG 9 North America Public Cloud Interface Market, 2022 - 2033, USD Million
FIG 10 North America Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
FIG 11 North America ASIC Market, 2022 - 2033, USD Million
FIG 12 North America CPU Market, 2022 - 2033, USD Million
FIG 13 North America FPGA Market, 2022 - 2033, USD Million
FIG 14 North America GPU Market, 2022 - 2033, USD Million
FIG 15 North America Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
FIG 16 North America Cloud Market, 2022 - 2033, USD Million
FIG 17 North America HPC Market, 2022 - 2033, USD Million
FIG 18 United States Data Center Accelerator Market Market, 2022 - 2033, USD Million
FIG 19 United States Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
FIG 20 United States Deep Learning Training Market, 2022 - 2033, USD Million
FIG 21 United States Enterprise Interface Market, 2022 - 2033, USD Million
FIG 22 United States Public Cloud Interface Market, 2022 - 2033, USD Million
FIG 23 United States Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
FIG 24 United States ASIC Market, 2022 - 2033, USD Million
FIG 25 United States CPU Market, 2022 - 2033, USD Million
FIG 26 United States FPGA Market, 2022 - 2033, USD Million
FIG 27 United States GPU Market, 2022 - 2033, USD Million
FIG 28 United States Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
FIG 29 United States Cloud Market, 2022 - 2033, USD Million
FIG 30 United States HPC Market, 2022 - 2033, USD Million
FIG 31 Canada Data Center Accelerator Market Market, 2022 - 2033, USD Million
FIG 32 Canada Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
FIG 33 Canada Deep Learning Training Market, 2022 - 2033, USD Million
FIG 34 Canada Enterprise Interface Market, 2022 - 2033, USD Million
FIG 35 Canada Public Cloud Interface Market, 2022 - 2033, USD Million
FIG 36 Canada Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
FIG 37 Canada ASIC Market, 2022 - 2033, USD Million
FIG 38 Canada CPU Market, 2022 - 2033, USD Million
FIG 39 Canada FPGA Market, 2022 - 2033, USD Million
FIG 40 Canada GPU Market, 2022 - 2033, USD Million
FIG 41 Canada Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
FIG 42 Canada Cloud Market, 2022 - 2033, USD Million
FIG 43 Canada HPC Market, 2022 - 2033, USD Million
FIG 44 Mexico Data Center Accelerator Market Market, 2022 - 2033, USD Million
FIG 45 Mexico Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
FIG 46 Mexico Deep Learning Training Market, 2022 - 2033, USD Million
FIG 47 Mexico Enterprise Interface Market, 2022 - 2033, USD Million
FIG 48 Mexico Public Cloud Interface Market, 2022 - 2033, USD Million
FIG 49 Mexico Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
FIG 50 Mexico ASIC Market, 2022 - 2033, USD Million
FIG 51 Mexico CPU Market, 2022 - 2033, USD Million
FIG 52 Mexico FPGA Market, 2022 - 2033, USD Million
FIG 53 Mexico GPU Market, 2022 - 2033, USD Million
FIG 54 Mexico Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
FIG 55 Mexico Cloud Market, 2022 - 2033, USD Million
FIG 56 Mexico HPC Market, 2022 - 2033, USD Million
FIG 57 Rest of North America Data Center Accelerator Market Market, 2022 - 2033, USD Million
FIG 58 Rest of North America Data Center Accelerator Market Market by Application, 2022 - 2033, USD Million
FIG 59 Rest of North America Deep Learning Training Market, 2022 - 2033, USD Million
FIG 60 Rest of North America Enterprise Interface Market, 2022 - 2033, USD Million
FIG 61 Rest of North America Public Cloud Interface Market, 2022 - 2033, USD Million
FIG 62 Rest of North America Data Center Accelerator Market Market by Processor, 2022 - 2033, USD Million
FIG 63 Rest of North America ASIC Market, 2022 - 2033, USD Million
FIG 64 Rest of North America CPU Market, 2022 - 2033, USD Million
FIG 65 Rest of North America FPGA Market, 2022 - 2033, USD Million
FIG 66 Rest of North America GPU Market, 2022 - 2033, USD Million
FIG 67 Rest of North America Data Center Accelerator Market Market by Type, 2022 - 2033, USD Million
FIG 68 Rest of North America Cloud Market, 2022 - 2033, USD Million
FIG 69 Rest of North America HPC Market, 2022 - 2033, USD Million