North America Large Language Models In Healthcare Market Size, Share & Industry Analysis Report By Deployment Mode (Web & Cloud-based, and On-premise), By Component (Software and GPT Platform, and Services), By End-use (Hospitals, and Pharmaceutical & Biotech Companies), By Application, By Country Outlook and Forecast, 2026 - 2033
Published Date : 02-Sep-2026 |
Pages: 256 |
Report Format: PDF + Excel |
COVID-19 Impact on the North America Large Language Models In Healthcare Market
The North America Large Language Models In Healthcare Market is expected to reach USD 4.6 billion by 2032, growing at a CAGR of 31.4% during (2026 – 2033).
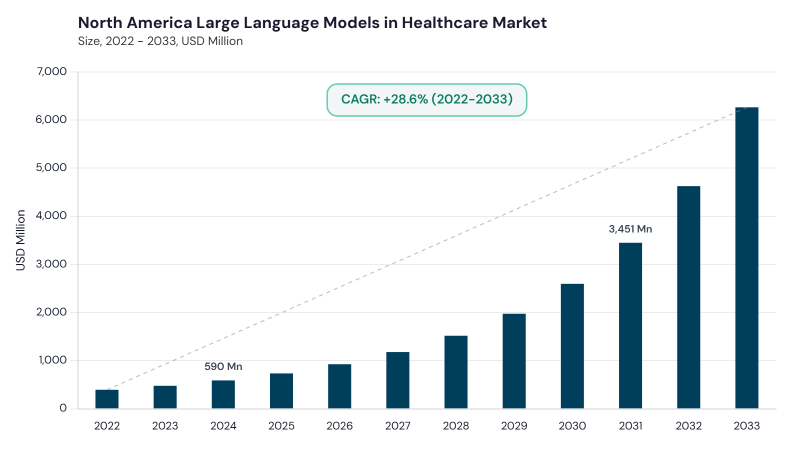
The North America Large Language Models In Healthcare Market developed from early natural language processing tools used for clinical documentation, transcription, and healthcare information retrieval. Initial solutions were limited by small datasets, restricted computing power, and narrow text-based functions that supported basic administrative and research tasks. Over time, deep learning, transformer architectures, electronic health records, and access to large clinical datasets enabled language models to understand complex medical terminology and clinical context. The market advanced as hospitals, pharmaceutical companies, telemedicine platforms, and payer organizations began using LLMs for documentation, decision support, patient engagement, and research workflows.
The North America Large Language Models In Healthcare Market is being shaped by the rising demand for clinical documentation automation, decision support, personalized care, drug discovery acceleration, and administrative workflow efficiency. Healthcare providers are using LLMs to summarize patient records, generate clinical notes, support care coordination, automate coding, assist virtual communication, and reduce provider burden. Demand is supported by healthcare digitization, EHR adoption, telehealth expansion, value-based care models, and growing emphasis on evidence-based decision-making. Vendors are focusing on secure cloud platforms, private LLM frameworks, specialty-specific models, explainability tools, interoperability with healthcare IT systems, and HIPAA-aligned data governance.
Deployment Mode Outlook
Based on Deployment Mode, the market is segmented into Web & Cloud-based and On-premise. The Web & Cloud-based market dominated the North America Large Language Models In Healthcare Market by Deployment Mode in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 3.4 billion by 2032, growing at a CAGR of 31.5 % during the forecast period. The On-premise market is expected to witness a CAGR of 31.1% during (2026 - 2033).
Web & Cloud-based deployment leads due to scalable infrastructure, faster implementation, remote accessibility, continuous model updates, and easier integration with healthcare applications. Cloud-based LLMs support clinical decision support, patient engagement, ambient documentation, medical summarization, large-scale analytics, and EHR-connected workflows across hospitals and distributed care settings. This model is particularly useful for healthcare providers seeking cost-efficient deployment, collaborative access, and rapid updates as medical knowledge evolves. On-premise deployment remains important for large hospital systems, research institutions, specialty clinics, and organizations prioritizing full data control, strict privacy governance, customized model tuning, lower latency, and secure handling of sensitive patient information.
Component Outlook
Based on Component, the market is segmented into Software and GPT Platform and Services. The Software and GPT Platform market dominated the North America Large Language Models In Healthcare Market by Component in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 3.1 billion by 2032, growing at a CAGR of 31.2 % during the forecast period. The Services market is expected to witness a CAGR of 31.8% during (2026 - 2033).
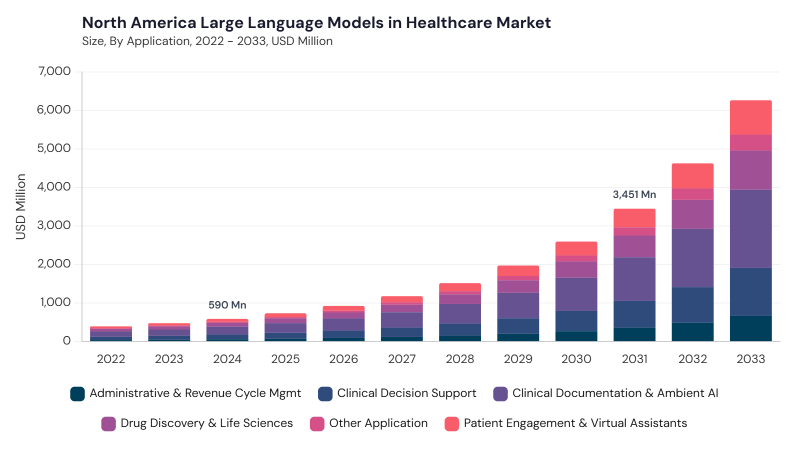
Software and GPT Platform leads due to rising adoption of healthcare-specific LLM platforms, medical language APIs, clinical documentation tools, decision-support engines, and GPT-based workflow applications. These platforms help healthcare organizations interpret unstructured clinical notes, generate summaries, automate documentation, support medical coding, and improve patient communication. Services remain important as providers require implementation, customization, integration, training, compliance consulting, model fine-tuning, data annotation, and ongoing support. Service providers also help healthcare organizations manage clinician adoption, workflow redesign, model monitoring, ethical governance, security controls, and continuous optimization of LLM-enabled healthcare applications.
End-use Outlook
Based on End-use, the market is segmented into Hospitals, Pharmaceutical & Biotech Companies, Physician Practices & Ambulatory Clinics, Payer, and Other End-use. The Hospitals market dominated the North America Large Language Models In Healthcare Market by End-use in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 1.8 billion by 2032, growing at a CAGR of 30.6 % during the forecast period. The Pharmaceutical & Biotech Companies market is expected to witness a CAGR of 30.7% during (2026 - 2033). Additionally, The Physician Practices & Ambulatory Clinics market is expected to witness highest CAGR of 31.9% during (2026 - 2033).
Hospitals lead due to extensive use of LLMs in clinical documentation, EHR management, patient triage, diagnostic support, care coordination, operational analytics, and administrative workflow automation. These systems help reduce clinician workload, improve documentation accuracy, accelerate information retrieval, and support evidence-based decision-making across complex care environments. Pharmaceutical & Biotech Companies use LLMs to analyze biomedical literature, identify biomarkers, support drug discovery, optimize clinical trial design, and automate regulatory documentation. Physician Practices & Ambulatory Clinics, Payer, and Other End-use areas add demand through visit summaries, patient communication, claims processing, fraud detection, member services, public health analytics, research support, medical coding, and telehealth integration.
Application Outlook
Based on Application, the market is segmented into Clinical Documentation & Ambient AI, Clinical Decision Support, Drug Discovery & Life Sciences, Patient Engagement & Virtual Assistants, Administrative & Revenue Cycle Management, and Other Application. Clinical Documentation & Ambient AI leads due to strong demand for automated note generation, conversation transcription, clinical summarization, coding support, and reduced administrative burden for physicians. These tools help capture patient-provider interactions, structure clinical records, improve documentation quality, and support reimbursement-related accuracy.
Clinical Decision Support follows as LLMs assist with guideline interpretation, diagnostic suggestions, treatment planning, risk stratification, and evidence synthesis from medical literature and patient records. Drug Discovery & Life Sciences, Patient Engagement & Virtual Assistants, Administrative & Revenue Cycle Management, and Other Application areas add demand through research automation, patient education, virtual care support, claims processing, billing automation, clinical trial recruitment, and healthcare planning.
Free Valuable Insights: The Global Large Language Models In Healthcare Market will hit USD 12.3 Billion billion by 2033, at a CAGR of 31.9%
Country Outlook
Based on Country, the market is segmented into US, Canada, Mexico, and Rest of North America. The US market dominated the North America Large Language Models In Healthcare Market by Country in 2025, and would continue to be a dominant market till 2033; thereby, achieving a market value of USD 3.5 billion by 2032, growing at a CAGR of 30.6 % during the forecast period. The Canada market is expected to witness a CAGR of 34.6% during (2026 - 2033). Additionally, The Mexico market is expected to witness a CAGR of 33.4% during (2026 - 2033).
The US leads due to strong AI innovation, advanced healthcare IT infrastructure, broad EHR adoption, large healthcare datasets, high investment in clinical AI, and rapid integration of LLMs across hospitals, pharma research, and digital health platforms. Canada supports market growth through AI research strength, bilingual healthcare needs, equity-focused digital care, telehealth adoption, and growing use of LLMs to improve access in underserved regions. Mexico is advancing through healthcare digitization, Spanish-language clinical AI development, staffing support needs, administrative automation, and growing interest in AI-based diagnostic and patient communication tools. Rest of North America benefits from multilingual healthcare demand, explainable AI adoption, secure deployment models, and wider integration of LLMs into clinical and operational workflows.
List of Key Companies Profiled
- Microsoft Corporation
- Abridge AI, Inc.
- Google LLC
- Amazon Web Services, Inc.
- Oracle Corporation
- Suki AI, Inc.
- OpenAI, L.L.C.
- Ambience Healthcare, Inc.
- Nabla Technologies, Inc.
- Hippocratic AI, Inc.
North America Large Language Models In Healthcare Market Report Segmentation
By Deployment Mode
- Web & Cloud-based
- On-premise
By Component
- Software and GPT Platform
- Services
By End-use
- Hospitals
- Pharmaceutical & Biotech Companies
- Physician Practices & Ambulatory Clinics
- Payer
- Other End-use
By Application
- Clinical Documentation & Ambient AI
- Clinical Decision Support
- Drug Discovery & Life Sciences
- Patient Engagement & Virtual Assistants
- Administrative & Revenue Cycle Mgmt
- Other Application
By Country
- US
- Canada
- Mexico
- Rest of North America
1.1 Market Overview
1.2 Key Factors Impacting Market
1.2.1 Market Drivers
1.2.2 Market Restraints
1.2.3 Market Opportunities
1.2.4 Market Challenges
1.2.5 Market Trends
1.2.6 State of Competition
1.2.7 Market Consolidation
1.2.8 Key Customer Criteria
1.3 Product Life Cycle
1.4 Segmentation By Data Center
1.4.1 Self-Build
1.4.2 Colocation
1.5 Segmentation By Cooling Technology
1.5.1 Air-Based Cooling
1.5.2 Liquid-Based Cooling
1.6 Segmentation By Solution
1.6.1 Storage
1.6.2 Server
1.6.3 Networking
1.6.4 Security
1.6.5 Other Solution
1.7 Segmentation By Country
1.7.1 US
1.7.1.1 Segmentation By Data Center Type
1.7.1.1.1 Self-Build
1.7.1.1.2 Colocation
1.7.1.2 Segmentation By Cooling Technology
1.7.1.2.1 Air-Based Cooling
1.7.1.2.2 Liquid-Based Cooling
1.7.1.3 Segmentation By Solution
1.7.1.3.1 Storage
1.7.1.3.2 Server
1.7.1.3.3 Networking
1.7.1.3.4 Security
1.7.1.3.5 Other Solution
1.7.2 Canada
1.7.2.1 Segmentation By Data Center Type
1.7.2.1.1 Self-Build
1.7.2.1.2 Colocation
1.7.2.2 Segmentation By Cooling Technology
1.7.2.2.1 Air-Based Cooling
1.7.2.2.2 Liquid-Based Cooling
1.7.2.3 Segmentation By Solution
1.7.2.3.1 Storage
1.7.2.3.2 Server
1.7.2.3.3 Networking
1.7.2.3.4 Security
1.7.2.3.5 Other Solution
1.7.3 Mexico
1.7.3.1 Segmentation By Data Center Type
1.7.3.1.1 Self-Build
1.7.3.1.2 Colocation
1.7.3.2 Segmentation By Cooling Technology
1.7.3.2.1 Air-Based Cooling
1.7.3.2.2 Liquid-Based Cooling
1.7.3.3 Segmentation By Solution
1.7.3.3.1 Storage
1.7.3.3.2 Server
1.7.3.3.3 Networking
1.7.3.3.4 Security
1.7.3.3.5 Other Solution
1.7.4 Rest of North America
1.7.4.1 Segmentation By Data Center Type
1.7.4.1.1 Self-Build
1.7.4.1.2 Colocation
1.7.4.2 Segmentation By Cooling Technology
1.7.4.2.1 Air-Based Cooling
1.7.4.2.2 Liquid-Based Cooling
1.7.4.3 Segmentation By Solution
1.7.4.3.1 Storage
1.7.4.3.2 Server
1.7.4.3.3 Networking
1.7.4.3.4 Security
1.7.4.3.5 Other Solution
Chapter 2. Company Snapshots
2.1 Amazon Web Services, Inc.
2.1.1 Business Overview
2.1.2 Key Information
2.1.3 Company Focus on Mega Data Center Market
2.1.4 Strategic Insights
2.1.5 Strategy Deployed
2.1.6 Product & Service Portfolio
2.1.7 Capability Overview
2.1.8 Technology & Innovation Focus
2.1.9 SWOT Analysis
2.1.10 Customers / End Users
2.1.11 Competitive Positioning
2.1.12 Key Differentiators
2.1.13 Portfolio Matrix
2.1.14 Analyst View
2.1.15 Future Outlook
2.2 Microsoft Corporation
2.2.1 Business Overview
2.2.2 Key Information
2.2.3 Company Focus on Mega Data Center Market
2.2.4 Strategic Insights
2.2.5 Strategy Deployed
2.2.6 Product & Service Portfolio
2.2.7 Capability Overview
2.2.8 Technology & Innovation Focus
2.2.9 SWOT Analysis
2.2.10 Customers / End Users
2.2.11 Competitive Positioning
2.2.12 Key Differentiators
2.2.13 Portfolio Matrix
2.2.14 Analyst View
2.2.15 Future Outlook
2.2.16 Business Overview
2.2.17 Key Information
2.2.18 Company Focus on Mega Data Center Market
2.2.19 Strategic Insights on Mega Data Center Market
2.2.20 Strategy Deployed
2.2.21 Product & Service Portfolio
2.2.22 Capability Overview
2.2.23 Technology & Innovation Focus
2.2.24 SWOT Analysis
2.2.25 Customers / End Users
2.2.26 Competitive Positioning
2.2.27 Key Differentiators
2.2.28 Portfolio Matrix
2.2.29 Analyst View
2.2.30 Future Outlook
2.3 Meta Platforms, Inc.
2.3.1 Business Overview
2.3.2 Key Information
2.3.3 Company Focus on Mega Data Center Market
2.3.4 Strategic Insights
2.3.5 Strategy Deployed
2.3.6 Product & Service Portfolio
2.3.7 Capability Overview
2.3.8 Technology & Innovation Focus
2.3.9 SWOT Analysis
2.3.10 Customers / End Users
2.3.11 Competitive Positioning
2.3.12 Key Differentiators
2.3.13 Portfolio Matrix
2.3.14 Analyst View
2.3.15 Future Outlook
2.4 Alibaba Cloud
2.4.1 Business Overview
2.4.2 Key Information
2.4.3 Company Focus on Mega Data Center Market
2.4.4 Strategic Insights
2.4.5 Strategy Deployed
2.4.6 Product & Service Portfolio
2.4.7 Capability Overview
2.4.8 Technology & Innovation Focus
2.4.9 SWOT Analysis
2.4.10 Customers / End Users
2.4.11 Competitive Positioning
2.4.12 Key Differentiators
2.4.13 Portfolio Matrix
2.4.14 Analyst View
2.4.15 Future Outlook
2.5 Digital Realty Trust, Inc.
2.5.1 Business Overview
2.5.2 Key Information
2.5.3 Company Focus on Mega Data Center Market
2.5.4 Strategic Insights
2.5.5 Strategy Deployed
2.5.6 Product & Service Portfolio
2.5.7 Capability Overview
2.5.8 Technology & Innovation Focus
2.5.9 SWOT Analysis
2.5.10 Customers / End Users
2.5.11 Competitive Positioning
2.5.12 Key Differentiators
2.5.13 Portfolio Matrix
2.5.14 Analyst View
2.5.15 Future Outlook
2.6 Oracle Corporation
2.6.1 Business Overview
2.6.2 Key Information
2.6.3 Company Focus on Mega Data Center Market
2.6.4 Strategic Insights
2.6.5 Strategy Deployed
2.6.6 Product & Service Portfolio
2.6.7 Capability Overview
2.6.8 Technology & Innovation Focus
2.6.9 SWOT Analysis
2.6.10 Customers / End Users
2.6.11 Competitive Positioning
2.6.12 Key Differentiators
2.6.13 Portfolio Matrix
2.6.14 Analyst View
2.6.15 Future Outlook
2.7 ViTrox Corporation Berhad
2.7.1 Business Overview
2.7.2 Key Information
2.7.3 Company Focus on Mega Data Center Market
2.7.4 Strategic Insights
2.7.5 Strategy Deployed
2.7.6 Product & Service Portfolio
2.7.7 Capability Overview
2.7.8 Technology & Innovation Focus
2.7.9 SWOT Analysis
2.7.10 Customers / End Users
2.7.11 Competitive Positioning
2.7.12 Key Differentiators
2.7.13 Portfolio Matrix
2.7.14 Analyst View
2.7.15 Future Outlook
2.8 Camtek Ltd.
2.8.1 Business Overview
2.8.2 Key Information
2.8.3 Company Focus on Mega Data Center Market
2.8.4 Strategic Insights
2.8.5 Strategy Deployed
2.8.6 Product & Service Portfolio
2.8.7 Capability Overview
2.8.8 Technology & Innovation Focus
2.8.9 SWOT Analysis
2.8.10 Customers / End Users
2.8.11 Competitive Positioning
2.8.12 Key Differentiators
2.8.13 Portfolio Matrix
2.8.14 Analyst View
2.8.15 Future Outlook
2.9 GÖPEL electronic GmbH
2.9.1 Business Overview
2.9.2 Key Information
2.9.3 Company Focus on Mega Data Center Market
2.9.4 Strategic Insights
2.9.5 Strategy Deployed
2.9.6 Product & Service Portfolio
2.9.7 Capability Overview
2.9.8 Technology & Innovation Focus
2.9.9 SWOT Analysis
2.9.10 Customers / End Users
2.9.11 Competitive Positioning
2.9.12 Key Differentiators
2.9.13 Portfolio Matrix
2.9.14 Analyst View
2.9.15 Future Outlook
Table 1 North America Mega Data Center Market Market, 2022 - 2033, USD Million
Table 2 North America Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
Table 3 North America Air-Based Cooling Market, 2022 - 2033, USD Million
Table 4 North America Liquid-Based Cooling Market, 2022 - 2033, USD Million
Table 5 North America Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
Table 6 North America Colocation Market, 2022 - 2033, USD Million
Table 7 North America Self-build Market, 2022 - 2033, USD Million
Table 8 North America Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
Table 9 North America Networking Market, 2022 - 2033, USD Million
Table 10 North America Other Solution Market, 2022 - 2033, USD Million
Table 11 North America Security Market, 2022 - 2033, USD Million
Table 12 North America Server Market, 2022 - 2033, USD Million
Table 13 North America Storage Market, 2022 - 2033, USD Million
Table 14 United States Mega Data Center Market Market, 2022 - 2033, USD Million
Table 15 United States Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
Table 16 United States Air-Based Cooling Market, 2022 - 2033, USD Million
Table 17 United States Liquid-Based Cooling Market, 2022 - 2033, USD Million
Table 18 United States Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
Table 19 United States Colocation Market, 2022 - 2033, USD Million
Table 20 United States Self-build Market, 2022 - 2033, USD Million
Table 21 United States Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
Table 22 United States Networking Market, 2022 - 2033, USD Million
Table 23 United States Other Solution Market, 2022 - 2033, USD Million
Table 24 United States Security Market, 2022 - 2033, USD Million
Table 25 United States Server Market, 2022 - 2033, USD Million
Table 26 United States Storage Market, 2022 - 2033, USD Million
Table 27 Canada Mega Data Center Market Market, 2022 - 2033, USD Million
Table 28 Canada Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
Table 29 Canada Air-Based Cooling Market, 2022 - 2033, USD Million
Table 30 Canada Liquid-Based Cooling Market, 2022 - 2033, USD Million
Table 31 Canada Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
Table 32 Canada Colocation Market, 2022 - 2033, USD Million
Table 33 Canada Self-build Market, 2022 - 2033, USD Million
Table 34 Canada Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
Table 35 Canada Networking Market, 2022 - 2033, USD Million
Table 36 Canada Other Solution Market, 2022 - 2033, USD Million
Table 37 Canada Security Market, 2022 - 2033, USD Million
Table 38 Canada Server Market, 2022 - 2033, USD Million
Table 39 Canada Storage Market, 2022 - 2033, USD Million
Table 40 Mexico Mega Data Center Market Market, 2022 - 2033, USD Million
Table 41 Mexico Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
Table 42 Mexico Air-Based Cooling Market, 2022 - 2033, USD Million
Table 43 Mexico Liquid-Based Cooling Market, 2022 - 2033, USD Million
Table 44 Mexico Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
Table 45 Mexico Colocation Market, 2022 - 2033, USD Million
Table 46 Mexico Self-build Market, 2022 - 2033, USD Million
Table 47 Mexico Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
Table 48 Mexico Networking Market, 2022 - 2033, USD Million
Table 49 Mexico Other Solution Market, 2022 - 2033, USD Million
Table 50 Mexico Security Market, 2022 - 2033, USD Million
Table 51 Mexico Server Market, 2022 - 2033, USD Million
Table 52 Mexico Storage Market, 2022 - 2033, USD Million
Table 53 Rest of North America Mega Data Center Market Market, 2022 - 2033, USD Million
Table 54 Rest of North America Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
Table 55 Rest of North America Air-Based Cooling Market, 2022 - 2033, USD Million
Table 56 Rest of North America Liquid-Based Cooling Market, 2022 - 2033, USD Million
Table 57 Rest of North America Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
Table 58 Rest of North America Colocation Market, 2022 - 2033, USD Million
Table 59 Rest of North America Self-build Market, 2022 - 2033, USD Million
Table 60 Rest of North America Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
Table 61 Rest of North America Networking Market, 2022 - 2033, USD Million
Table 62 Rest of North America Other Solution Market, 2022 - 2033, USD Million
Table 63 Rest of North America Security Market, 2022 - 2033, USD Million
Table 64 Rest of North America Server Market, 2022 - 2033, USD Million
Table 65 Rest of North America Storage Market, 2022 - 2033, USD Million
List of Figures
FIG 1 Key Factors Impacting Market
FIG 2 Market Consolidation
FIG 3 Key Customer Criteria
FIG 4 Product Life Cycle
FIG 5 North America Mega Data Center Market Market, 2022 - 2033, USD Million
FIG 6 North America Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
FIG 7 North America Air-Based Cooling Market, 2022 - 2033, USD Million
FIG 8 North America Liquid-Based Cooling Market, 2022 - 2033, USD Million
FIG 9 North America Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
FIG 10 North America Colocation Market, 2022 - 2033, USD Million
FIG 11 North America Self-build Market, 2022 - 2033, USD Million
FIG 12 North America Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
FIG 13 North America Networking Market, 2022 - 2033, USD Million
FIG 14 North America Other Solution Market, 2022 - 2033, USD Million
FIG 15 North America Security Market, 2022 - 2033, USD Million
FIG 16 North America Server Market, 2022 - 2033, USD Million
FIG 17 North America Storage Market, 2022 - 2033, USD Million
FIG 18 United States Mega Data Center Market Market, 2022 - 2033, USD Million
FIG 19 United States Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
FIG 20 United States Air-Based Cooling Market, 2022 - 2033, USD Million
FIG 21 United States Liquid-Based Cooling Market, 2022 - 2033, USD Million
FIG 22 United States Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
FIG 23 United States Colocation Market, 2022 - 2033, USD Million
FIG 24 United States Self-build Market, 2022 - 2033, USD Million
FIG 25 United States Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
FIG 26 United States Networking Market, 2022 - 2033, USD Million
FIG 27 United States Other Solution Market, 2022 - 2033, USD Million
FIG 28 United States Security Market, 2022 - 2033, USD Million
FIG 29 United States Server Market, 2022 - 2033, USD Million
FIG 30 United States Storage Market, 2022 - 2033, USD Million
FIG 31 Canada Mega Data Center Market Market, 2022 - 2033, USD Million
FIG 32 Canada Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
FIG 33 Canada Air-Based Cooling Market, 2022 - 2033, USD Million
FIG 34 Canada Liquid-Based Cooling Market, 2022 - 2033, USD Million
FIG 35 Canada Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
FIG 36 Canada Colocation Market, 2022 - 2033, USD Million
FIG 37 Canada Self-build Market, 2022 - 2033, USD Million
FIG 38 Canada Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
FIG 39 Canada Networking Market, 2022 - 2033, USD Million
FIG 40 Canada Other Solution Market, 2022 - 2033, USD Million
FIG 41 Canada Security Market, 2022 - 2033, USD Million
FIG 42 Canada Server Market, 2022 - 2033, USD Million
FIG 43 Canada Storage Market, 2022 - 2033, USD Million
FIG 44 Mexico Mega Data Center Market Market, 2022 - 2033, USD Million
FIG 45 Mexico Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
FIG 46 Mexico Air-Based Cooling Market, 2022 - 2033, USD Million
FIG 47 Mexico Liquid-Based Cooling Market, 2022 - 2033, USD Million
FIG 48 Mexico Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
FIG 49 Mexico Colocation Market, 2022 - 2033, USD Million
FIG 50 Mexico Self-build Market, 2022 - 2033, USD Million
FIG 51 Mexico Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
FIG 52 Mexico Networking Market, 2022 - 2033, USD Million
FIG 53 Mexico Other Solution Market, 2022 - 2033, USD Million
FIG 54 Mexico Security Market, 2022 - 2033, USD Million
FIG 55 Mexico Server Market, 2022 - 2033, USD Million
FIG 56 Mexico Storage Market, 2022 - 2033, USD Million
FIG 57 Rest of North America Mega Data Center Market Market, 2022 - 2033, USD Million
FIG 58 Rest of North America Mega Data Center Market Market by Cooling Technology, 2022 - 2033, USD Million
FIG 59 Rest of North America Air-Based Cooling Market, 2022 - 2033, USD Million
FIG 60 Rest of North America Liquid-Based Cooling Market, 2022 - 2033, USD Million
FIG 61 Rest of North America Mega Data Center Market Market by Data Center Type, 2022 - 2033, USD Million
FIG 62 Rest of North America Colocation Market, 2022 - 2033, USD Million
FIG 63 Rest of North America Self-build Market, 2022 - 2033, USD Million
FIG 64 Rest of North America Mega Data Center Market Market by Solution, 2022 - 2033, USD Million
FIG 65 Rest of North America Networking Market, 2022 - 2033, USD Million
FIG 66 Rest of North America Other Solution Market, 2022 - 2033, USD Million
FIG 67 Rest of North America Security Market, 2022 - 2033, USD Million
FIG 68 Rest of North America Server Market, 2022 - 2033, USD Million
FIG 69 Rest of North America Storage Market, 2022 - 2033, USD Million